RetireShield Guide · 2026–2027 Edition
Your savings are safe at the bank. They could also be earning more. Here's how to build a ladder in one afternoon.
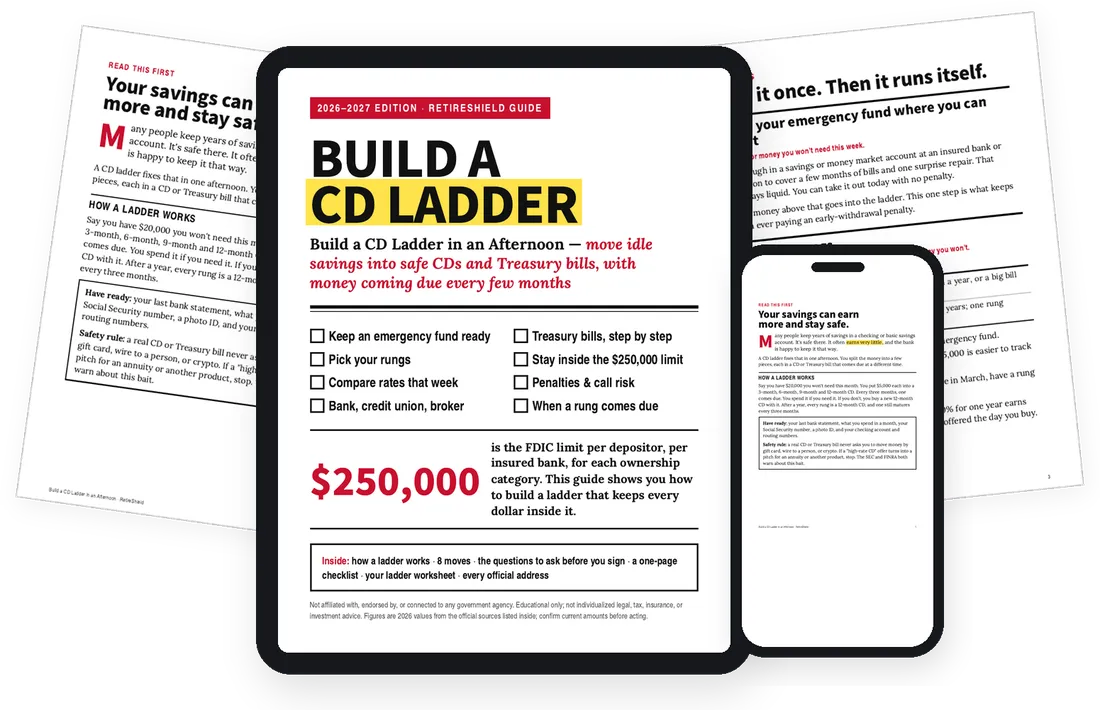
Many people keep years of savings in checking or basic savings, where it often earns very little. A CD ladder splits that money into a few safe pieces that come due every few months. This guide walks you through it, step by step.
Sound familiar?
Your savings sit safe. And they earn very little.
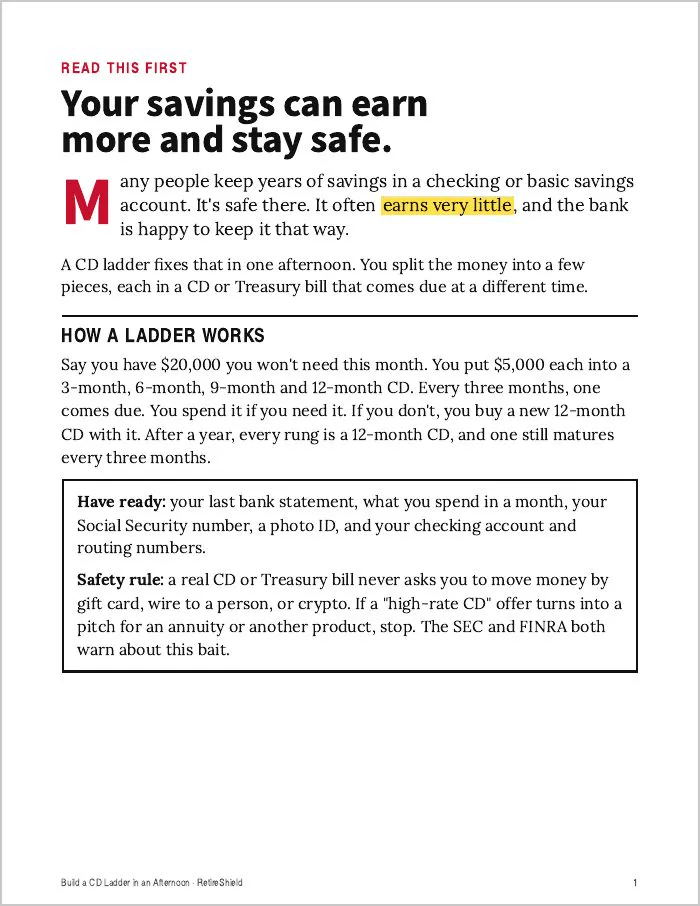
Years of savings in a checking or basic savings account. It's safe there. It often earns very little, and the bank is happy to keep it that way.
- Savings parked in an account that pays almost nothing
- Not sure what a good rate looks like this week
- Worried about tying money up and paying a penalty
- More than $250,000 at one bank, counting every account
What you get
Eight moves. Build it once, then it runs itself.
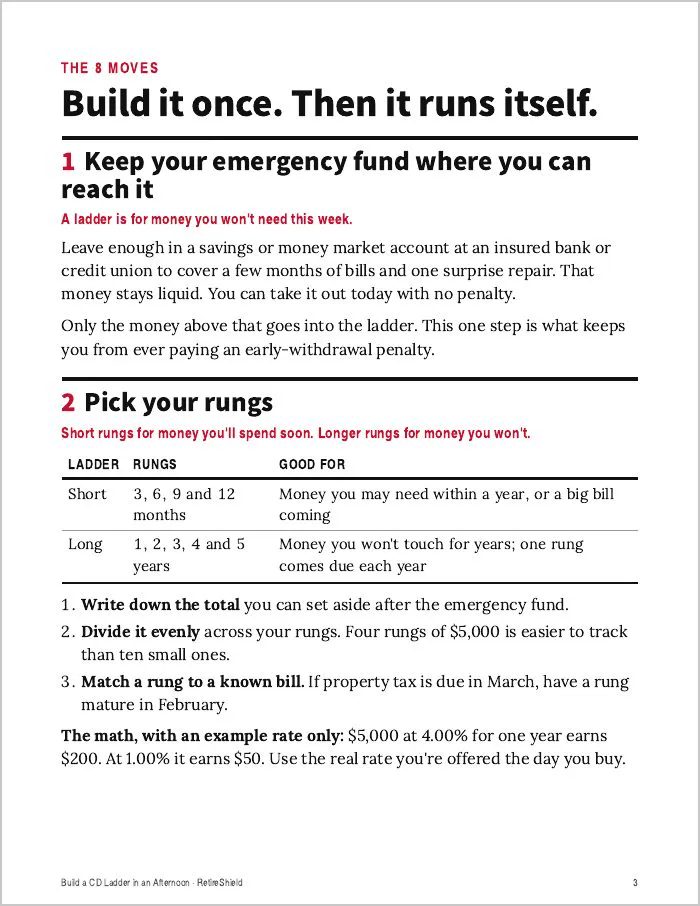
- Keep your emergency fund where you can reach it, so you never pay a penalty
- Pick your rungs: 3 to 12 months, or 1 to 5 years
- Compare rates the week you buy, with the questions to ask every bank
- Bank and credit union CDs, checked for insurance first
- Treasury bills from $100, with interest free of state and local income tax
- Stay inside the $250,000 limit at every bank
- Penalties and call risk, read before you sign
- When a rung comes due: spend it or roll it, before it renews on its own
What's inside
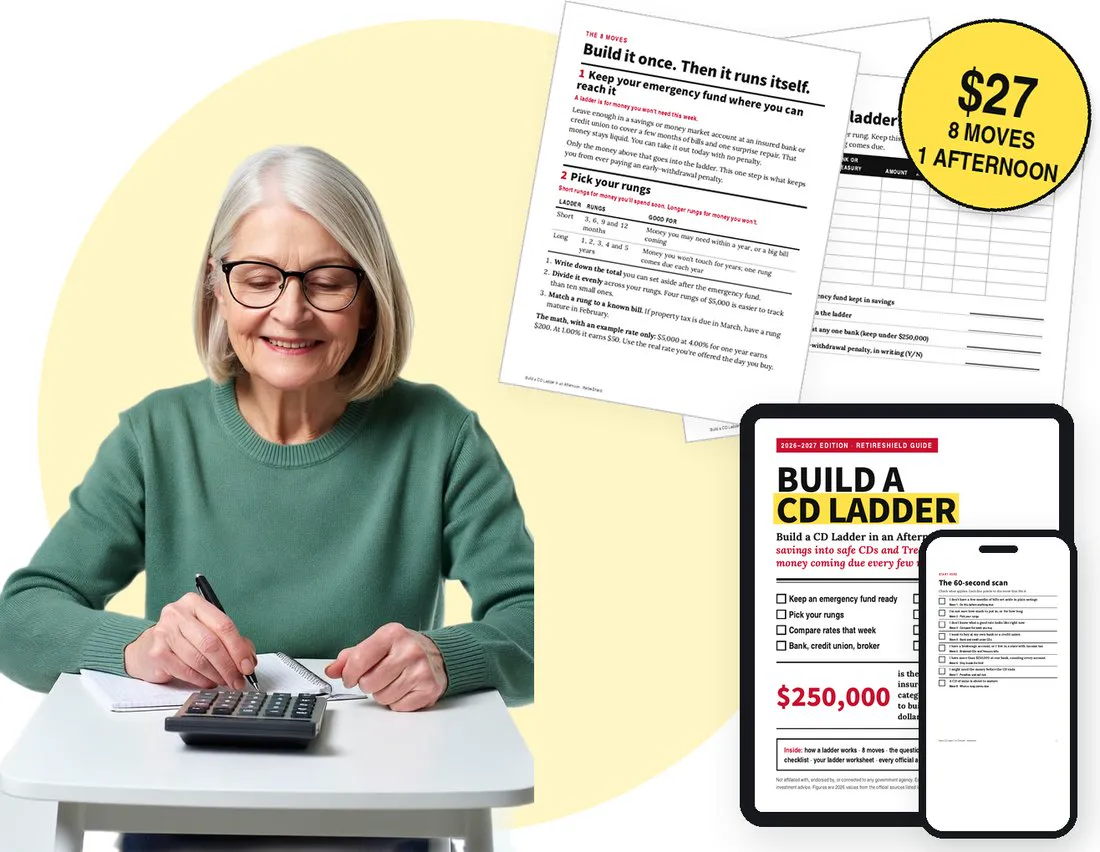
What's in the guide.
How a ladder works
One plain example, and the safety rule that keeps you away from bait offers.
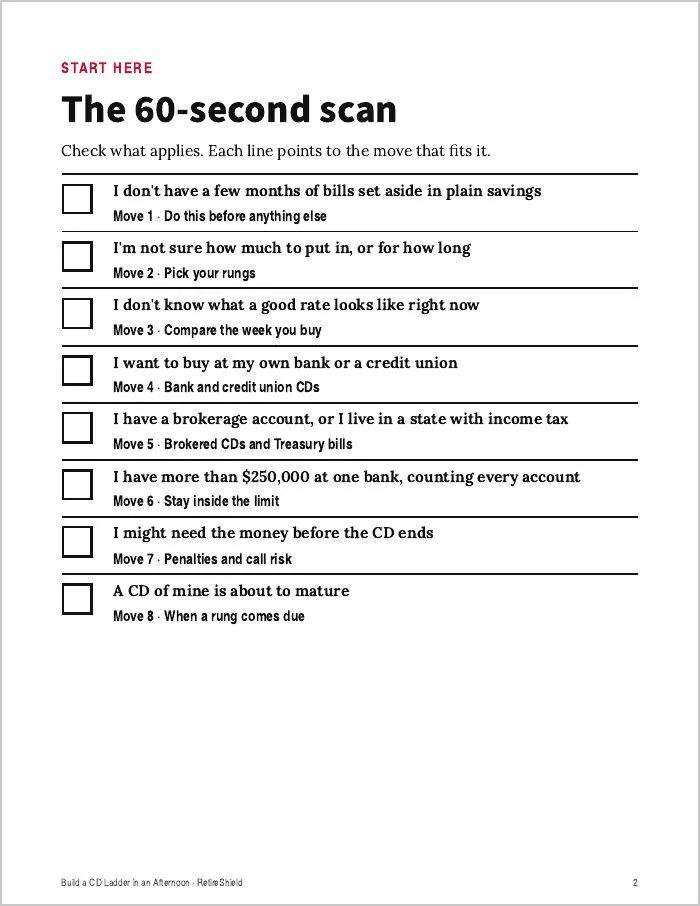
The 60-second scan
Tick what fits you. Each line points to the move to do first.
Step by step, with official links
Where to buy, what to ask, and how to stay insured.
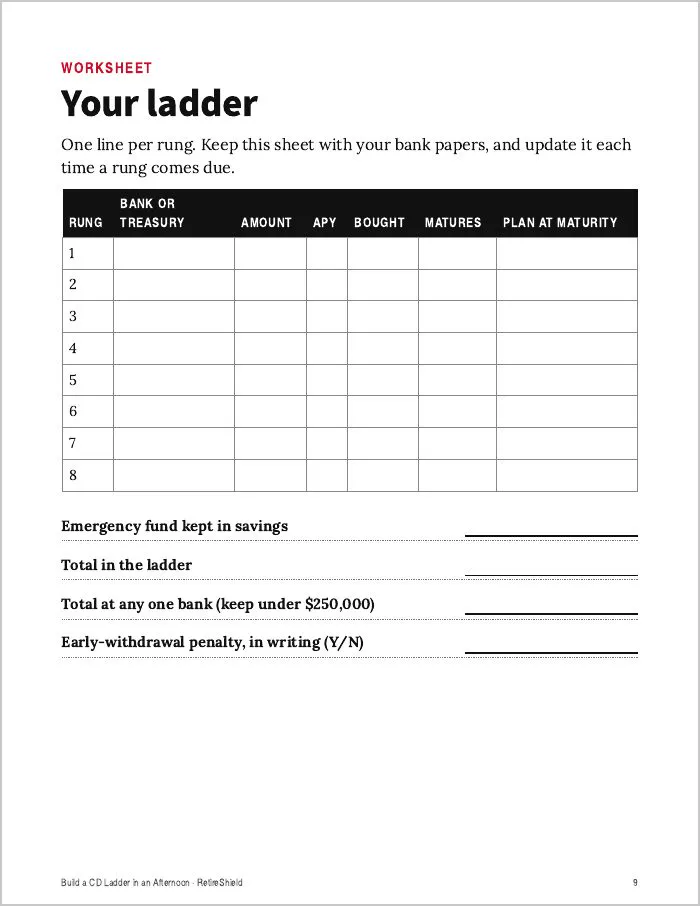
Your ladder
One line per rung. Bank, amount, APY, maturity date, and your plan.
FDIC, NCUA, Treasury, IRS
Checked October 2026. No old rates, only the pages that publish the current ones.
Large-print and audio editions
The same guide in big type, and read aloud (about 10 minutes). Listen on any phone, tablet or computer.
Look inside
Real pages from the guide.
How it works
Build a CD Ladder in an Afternoon
Card, Apple Pay or PayPal · secure checkout
Instant download, large print and audio included, 30-day money-back promise.
PROMISE
Read it. Use it. If it isn't for you, get every penny back.
Email us within 30 days for a full refund. You keep the files.
Questions
Is my money safe in a ladder?
CDs at insured banks and credit unions are covered up to $250,000 per depositor, per bank, for each ownership category. Treasury bills are a debt of the U.S. government. The guide shows how to keep every dollar inside the limit.
What if I need the money early?
Bank CDs charge an early-withdrawal penalty, so the guide has you keep an emergency fund in plain savings first. Only the money above that goes into the ladder.
When do I get it?
Immediately. The download appears on your screen the moment you pay, and a copy is emailed to you at once.
Is this a subscription?
No. It's one payment. There is nothing recurring and nothing to cancel.
Is it easy to read?
Yes. Plain English, short sections, and large-print and audio editions are included. It opens on any phone, tablet or computer, and prints cleanly.
What if it's not for me?
Email us within 30 days for a full refund. Keep the files.
RetireShield is independent and is not affiliated with, endorsed by, or connected to any government agency, bank or brokerage. This product provides educational information, not financial, tax, legal or investment advice.
Put your savings to work. One afternoon, $27.
Instant download, large print and audio included, 30-day money-back promise.
Get the guide — $27