RetireShield Guide · 2026–2027 Edition
Give the same gift to charity. Pay less tax on it.
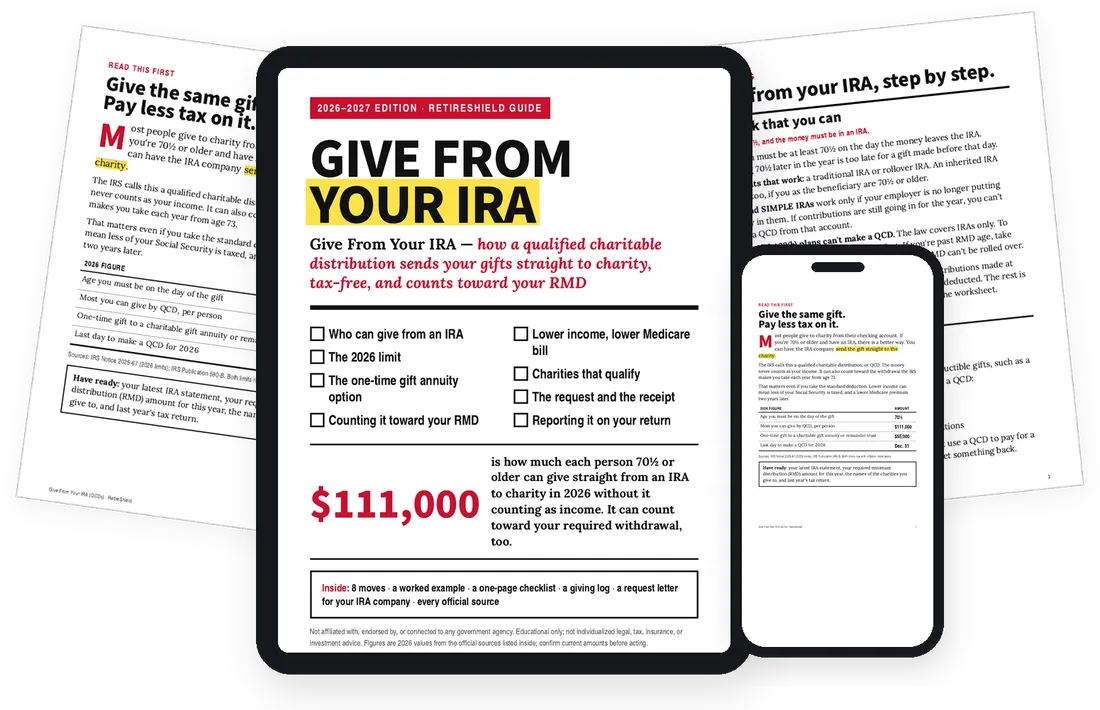
Most people give from their checking account. If you're 70½ or older and have an IRA, there is a better way. The IRA company sends the gift straight to the charity, and the money never counts as your income. This guide shows you how, step by step.
Sound familiar?
You give to charity every year. The IRS counts it as your income.
You take your required withdrawal, it lands in your bank, and then you write the checks. That money is already taxable. A gift made the other way never counts as income at all.
- Writing charity checks from your bank account
- Taking a required withdrawal you don't need
- Taking the standard deduction, so gifts don't lower your tax
- Income close to a Medicare surcharge line
What you get
Eight moves, from checking you qualify to filing it right.
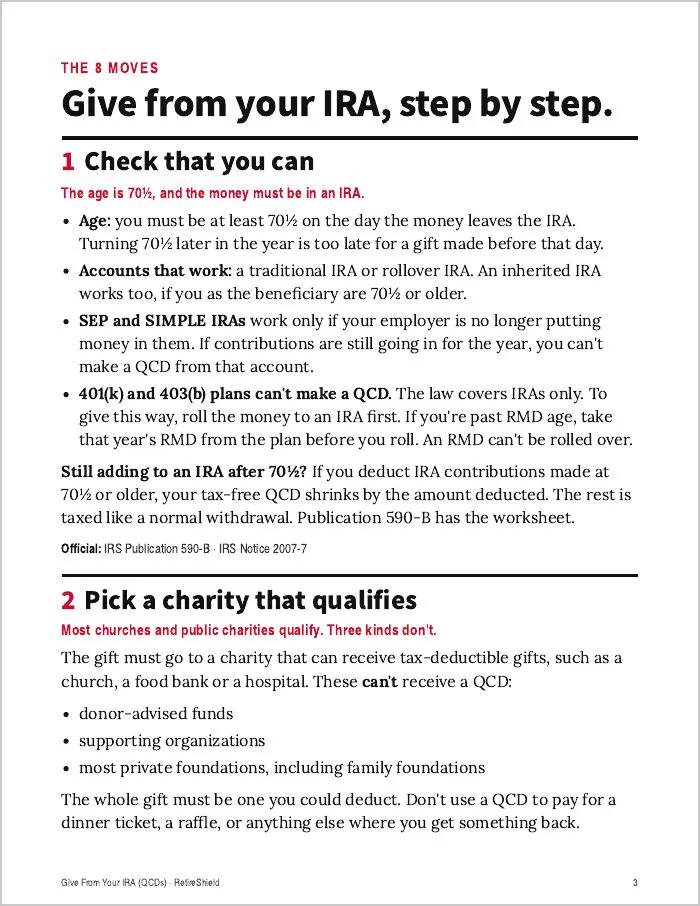
- Check that you can: the age, and which accounts work
- Pick a charity that qualifies, and the three kinds that don't
- Know the limits, including the one-time gift annuity option
- Let the gift cover your RMD, the withdrawal you must take anyway
- See what it saves on Social Security tax and your Medicare premium
- It works with the standard deduction. No need to itemize
- Ask your IRA company the right way, so it isn't a taxable withdrawal
- Report it right at tax time, even when your form doesn't say QCD
What's inside
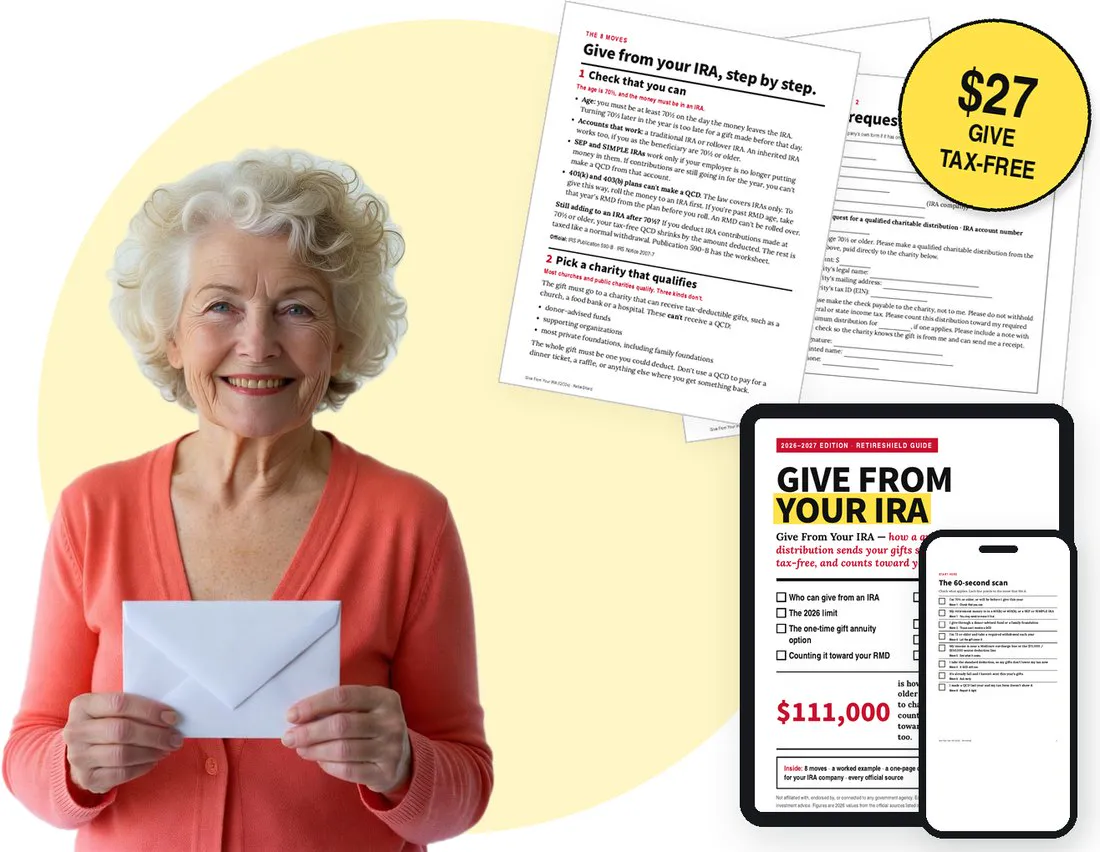
What's in the guide.
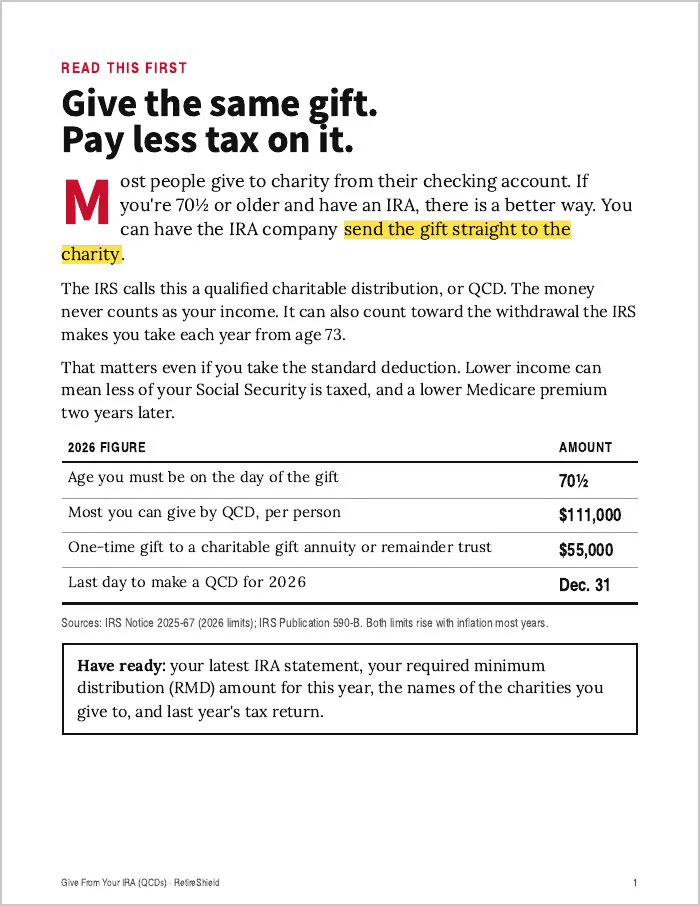
The 2026 figures
The age, the limit, the one-time option and the deadline, on one table.
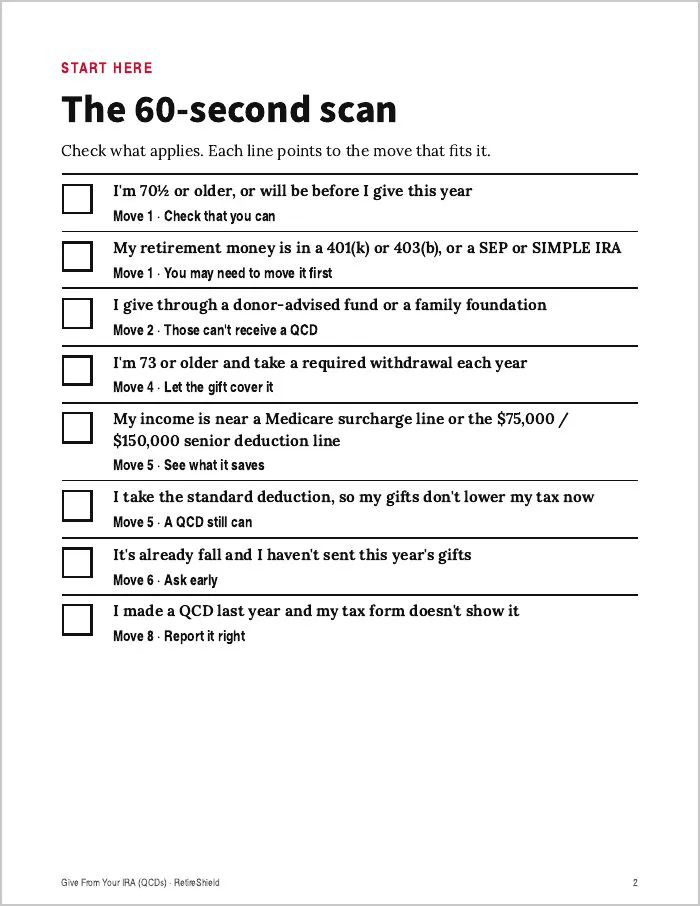
The 60-second scan
Tick what fits you. Each line points to the move to do first.
Step by step, with a worked example
Same gift, two ways. See what changes on the tax return.
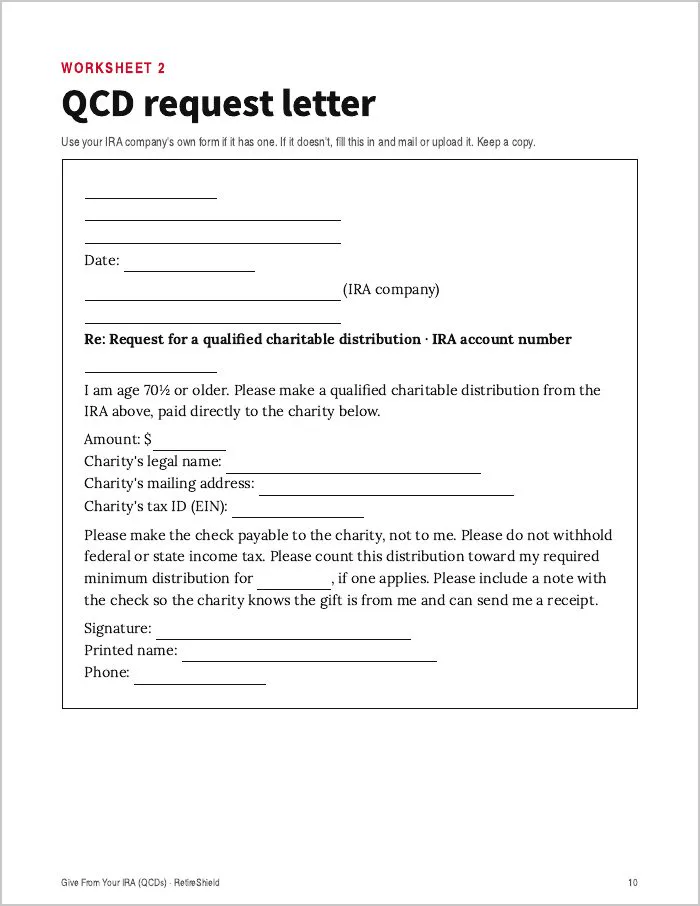
Giving log and request letter
Track each gift, and a letter to send your IRA company if it has no form.
IRS publications and notices
Checked October 2026. Every figure linked to the page that publishes it.
Large-print and audio editions
The same guide in big type, and read aloud (about 14 minutes). Listen on any phone, tablet or computer.
Look inside
Real pages from the guide.
How it works
Give From Your IRA (QCDs)
Card, Apple Pay or PayPal · secure checkout
Instant download, large print and audio included, 30-day money-back promise.
PROMISE
Read it. Use it. If it isn't for you, get every penny back.
Email us within 30 days for a full refund. You keep the files.
Questions
I take the standard deduction. Does this still help?
Yes. A QCD lowers your income itself, so you get the full benefit without itemizing. Lower income can mean less of your Social Security is taxed, and a lower Medicare premium two years later.
Is this tax advice?
No. The guide is educational and explains the IRS rules in plain English. For your own situation, and before any gift annuity or trust gift, talk with a tax professional.
When do I get it?
Immediately. The download appears on your screen the moment you pay, and a copy is emailed to you at once.
Is this a subscription?
No. It's one payment. There is nothing recurring and nothing to cancel.
Is it easy to read?
Yes. Plain English, short sections, and large-print and audio editions are included. It opens on any phone, tablet or computer, and prints cleanly.
What if it's not for me?
Email us within 30 days for a full refund. Keep the files.
RetireShield is independent and is not affiliated with, endorsed by, or connected to the IRS or any government agency. This product provides educational information, not financial, tax, legal or investment advice.
Give more. Keep more. $27.
Instant download, large print and audio included, 30-day money-back promise.
Get the guide — $27