Keep-It Step 4 · 2026–2027 Edition
Your house is your biggest bill and your biggest asset. Here's how to pay less on one and protect the other.
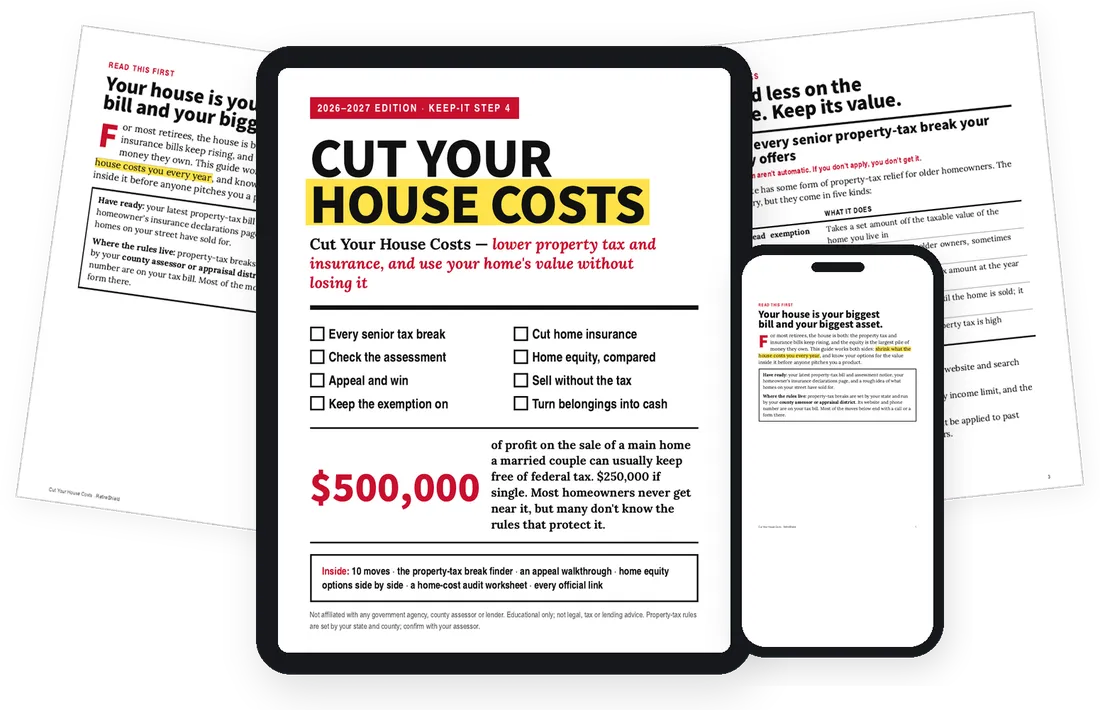
Property tax and insurance keep rising, and the equity is the largest pile of money most retirees own. This guide works both sides. Shrink what the house costs you every year, and know your options for its value before anyone pitches you a product.
Sound familiar?
The tax bill goes up every year. The break you qualify for never shows up.
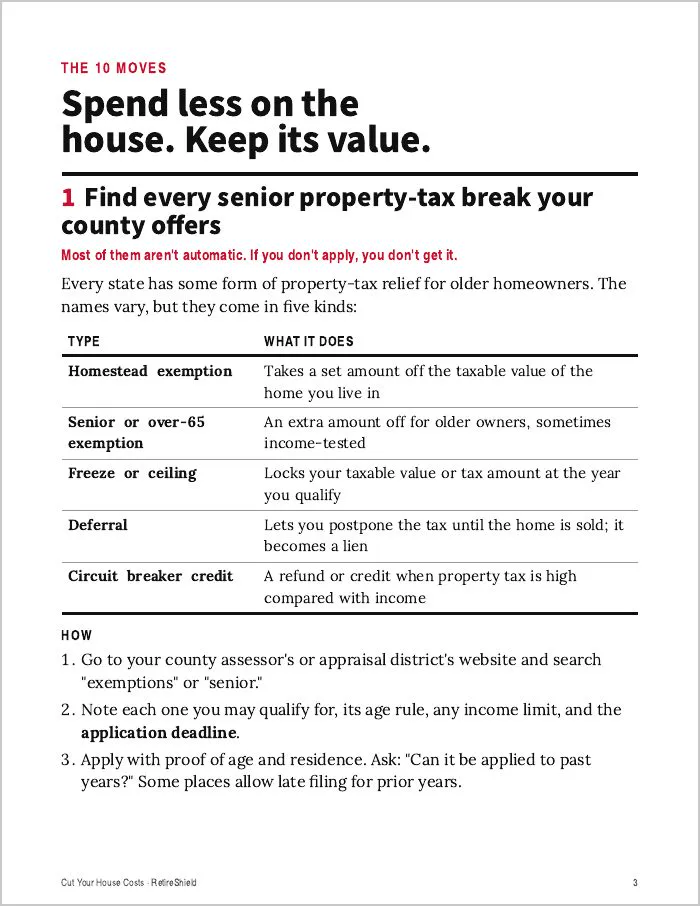
Every state has some form of property-tax relief for older homeowners. Most of it isn't automatic. If you don't apply, you don't get it. Meanwhile insurance premiums have climbed fast.
- Turned 65 and never applied for a senior tax break
- An assessed value higher than what homes on your street sell for
- Home insurance you haven't shopped in years
- Calls and letters offering cash for your house
What you get
Ten moves to spend less on the house and keep its value.
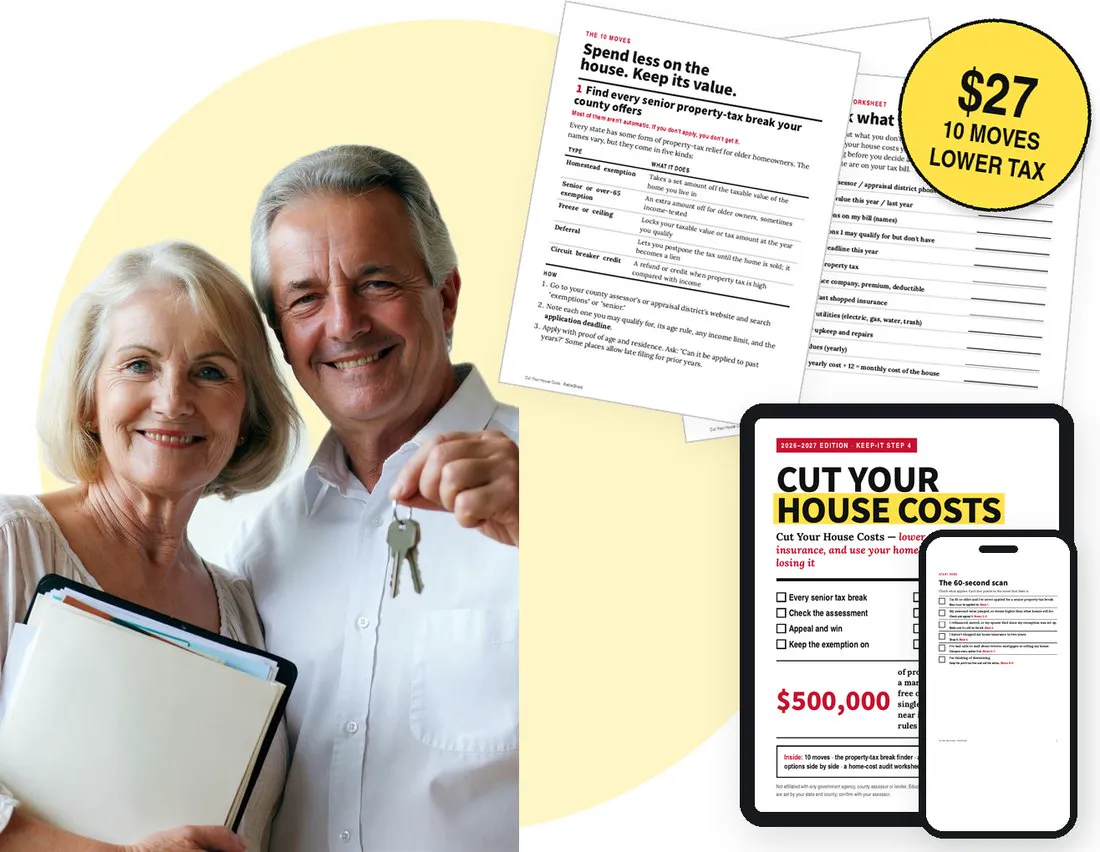
- Every senior property-tax break: the five kinds, and how to apply
- Mistakes on your property card that raise your value every year
- An assessment appeal, with the words to use at the hearing
- Your exemption still on the bill after a refinance, a trust or a spouse's death
- A lower home insurance bill by shopping and asking for every discount
- Home equity options compared, from a HELOC to a reverse mortgage
- Selling without the tax: up to $250,000 of profit, or $500,000 for a couple
- Turning belongings into cash when you downsize
What's inside
What's in the guide.
Where the rules live
Your county assessor runs the breaks. Its number is on your tax bill.
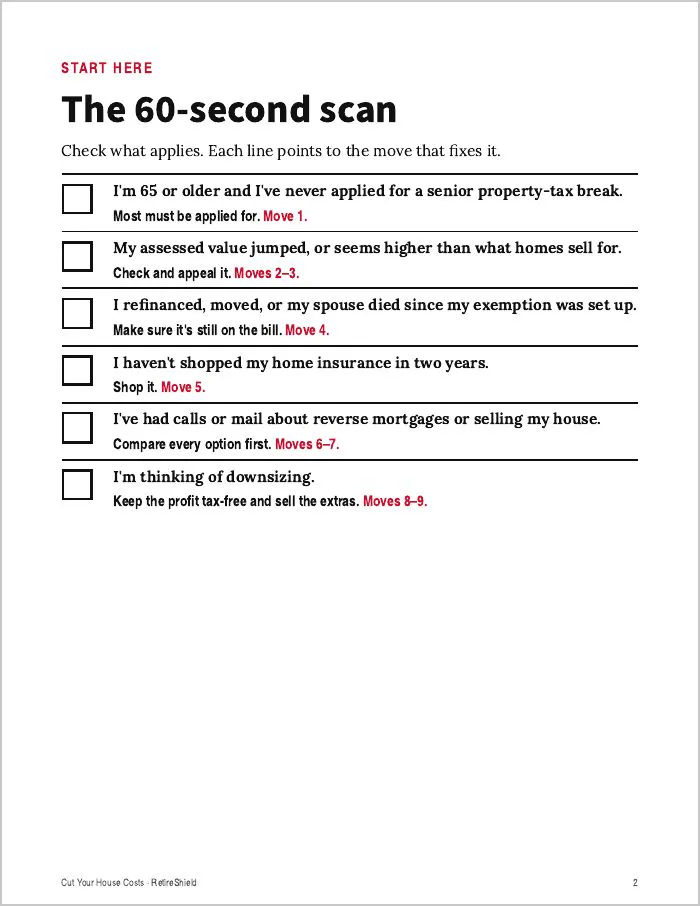
The 60-second scan
Tick what applies. Each line points to the move that fixes it.
The break finder and the appeal
The five kinds of relief, the steps to appeal, and what to say.
Home equity options side by side
How each one works, and what to watch out for.
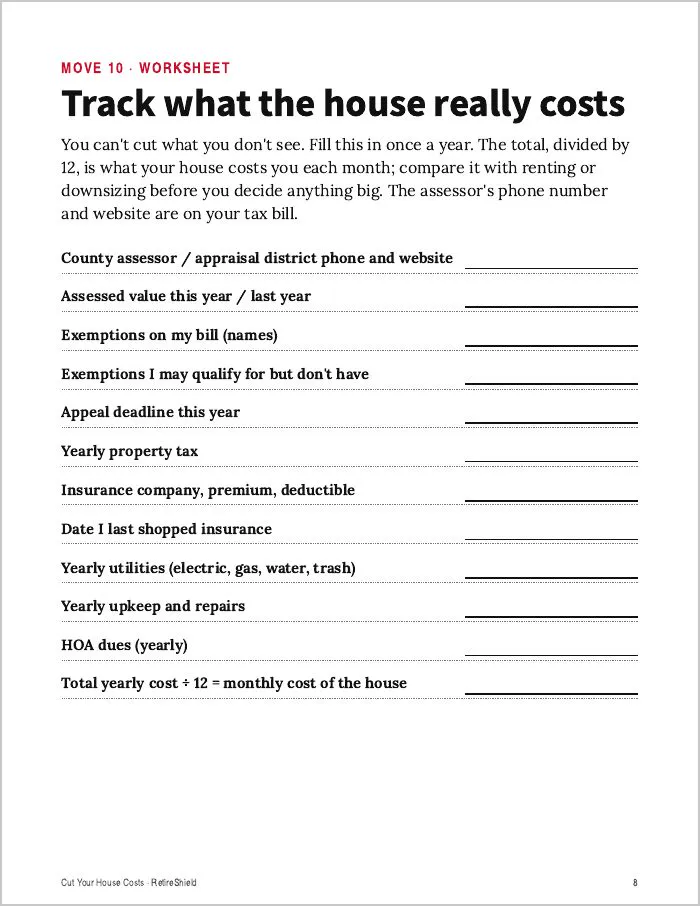
The home-cost audit
What the house really costs you each month. Fill it in once a year.
Large-print and audio editions
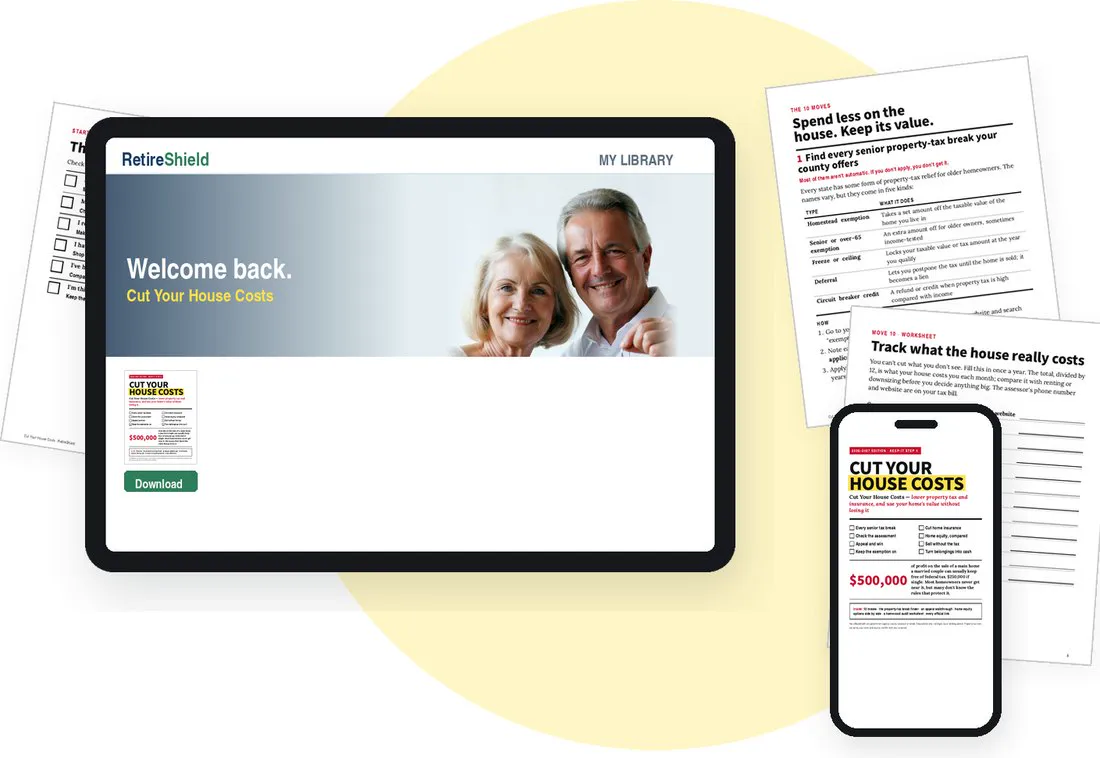
The same guide in big type, and read aloud (about 10 minutes). Listen on any phone, tablet or computer.
Look inside
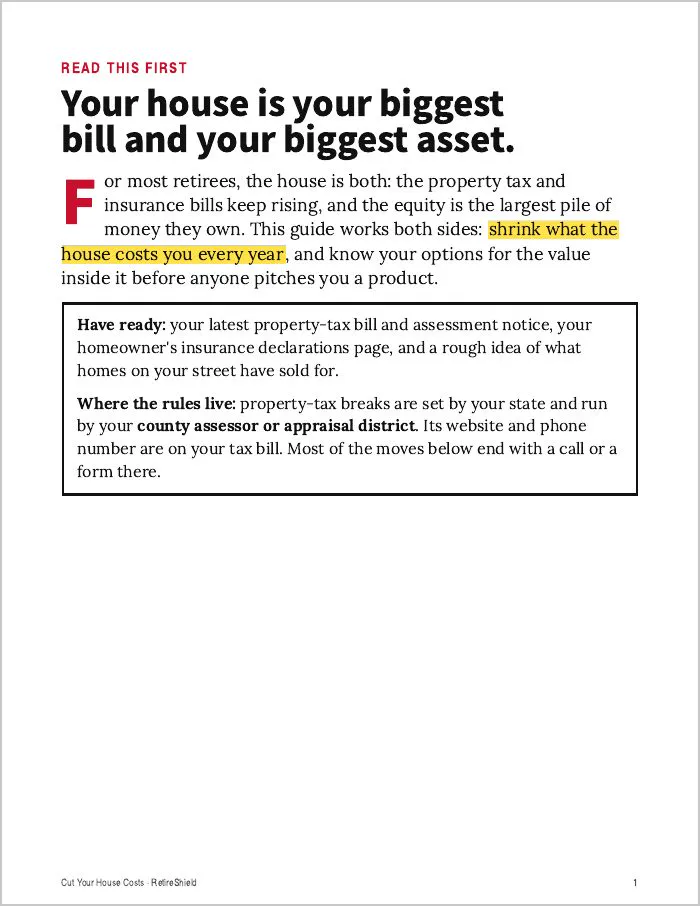
Real pages from the guide.
How it works
Cut Your House Costs
Card, Apple Pay or PayPal · secure checkout
Instant download, large print and audio included, 30-day money-back promise.
PROMISE
Read it. Use it. If it isn't for you, get every penny back.
Email us within 30 days for a full refund. You keep the files.
Questions
Does this work in my state?
Property-tax breaks are set by your state and run by your county assessor or appraisal district. The guide shows the five kinds of relief and how to find yours on your county's website. Your assessor has the exact amounts and deadlines.
Does it tell me to get a reverse mortgage?
No. It lays out each home equity option side by side, with how it works and what to watch out for, so you can compare before anyone pitches you. Before a federally insured reverse mortgage, you must meet with a HUD-approved counselor.
When do I get it?
Immediately. The download appears on your screen the moment you pay, and a copy is emailed to you at once.
Is this a subscription?
No. It's one payment. There is nothing recurring and nothing to cancel.
Is it easy to read?
Yes. Plain English, short sections, and large-print and audio editions are included. It opens on any phone, tablet or computer, and prints cleanly.
What if it's not for me?
Email us within 30 days for a full refund. Keep the files.
RetireShield is independent and is not affiliated with, endorsed by, or connected to any government agency, county assessor or lender. This product provides educational information, not legal, tax, lending, insurance or financial advice.
Spend less on the house. $27.
Instant download, large print and audio included, 30-day money-back promise.
Get the guide — $27