Keep-It Step 3 · 2026–2027 Edition
Medicare costs change every January. Here's how to stop paying more than you have to.
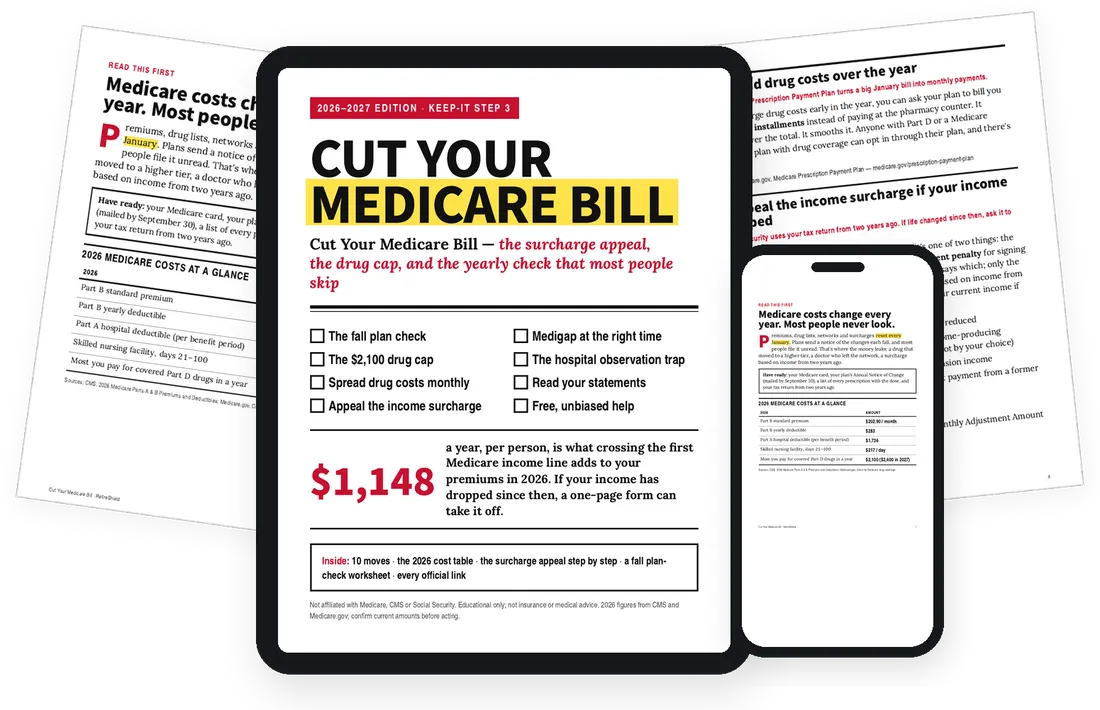
Premiums, drug lists, networks and surcharges reset every year. Plans mail a notice of the changes each fall, and most people file it unread. This guide shows 10 moves to pay less for the same care, with the 2026 figures.
Sound familiar?
The notice that changes your bill comes every fall. Most people never read it.
That's where the money leaks. A drug that moved to a higher tier. A doctor who left the network. A surcharge based on income from two years ago.
- A surcharge based on income you no longer have
- A drug that moved to a higher tier on your plan
- A doctor who left your plan's network
- A hospital stay that counted only as "observation"
What you get
Ten moves to pay less for the same care.
- The fall plan check: compare plans by total yearly cost for your exact drugs
- The $2,100 drug cap for 2026, and what counts toward it
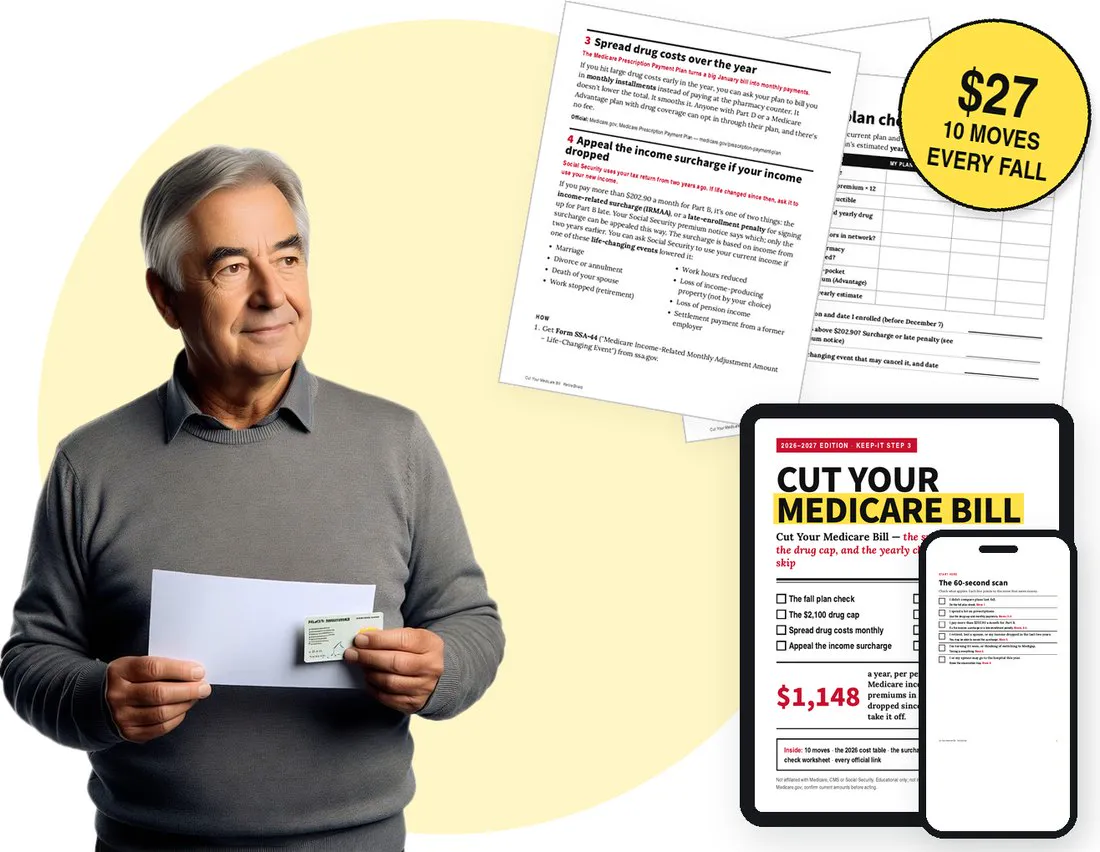
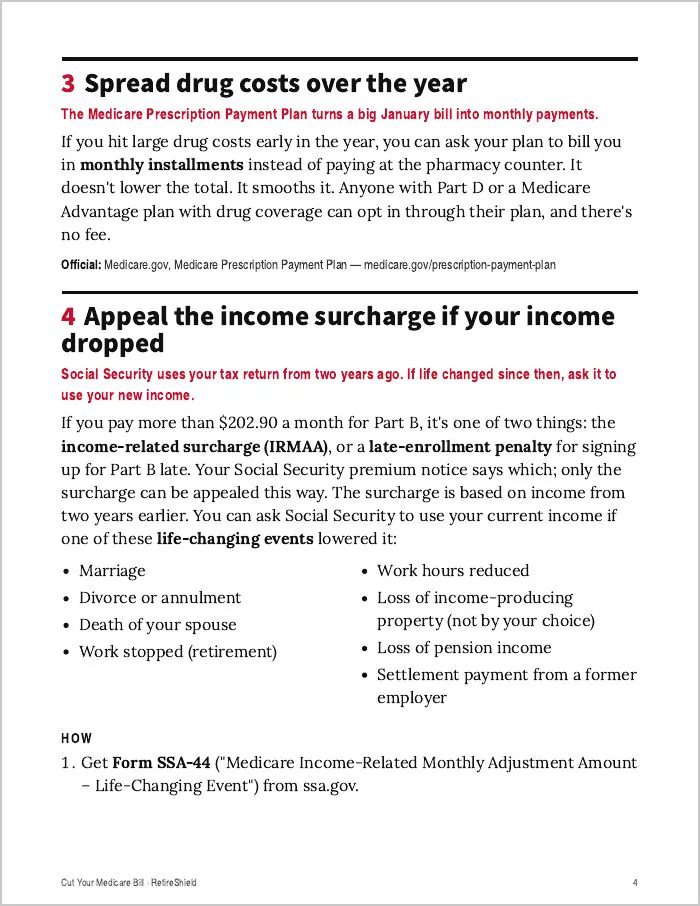
- Monthly drug payments in place of one big bill early in the year, with no fee
- The surcharge appeal with Form SSA-44 after retirement, divorce or a spouse's death
- Big one-time income planned around the surcharge line
- Medigap at the right moment, while no insurer can turn you down
- The hospital observation trap, and the question to ask every day
- Free, unbiased help from SHIP counselors in every state
What's inside
What's in the guide.
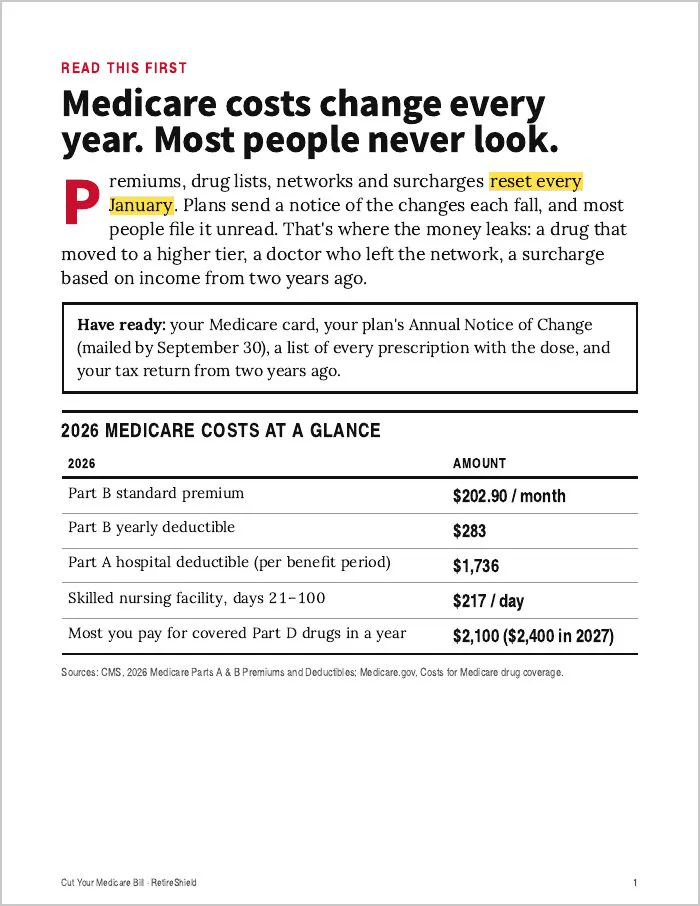
2026 Medicare costs at a glance
Premium, deductibles, skilled nursing and the drug cap on one table.
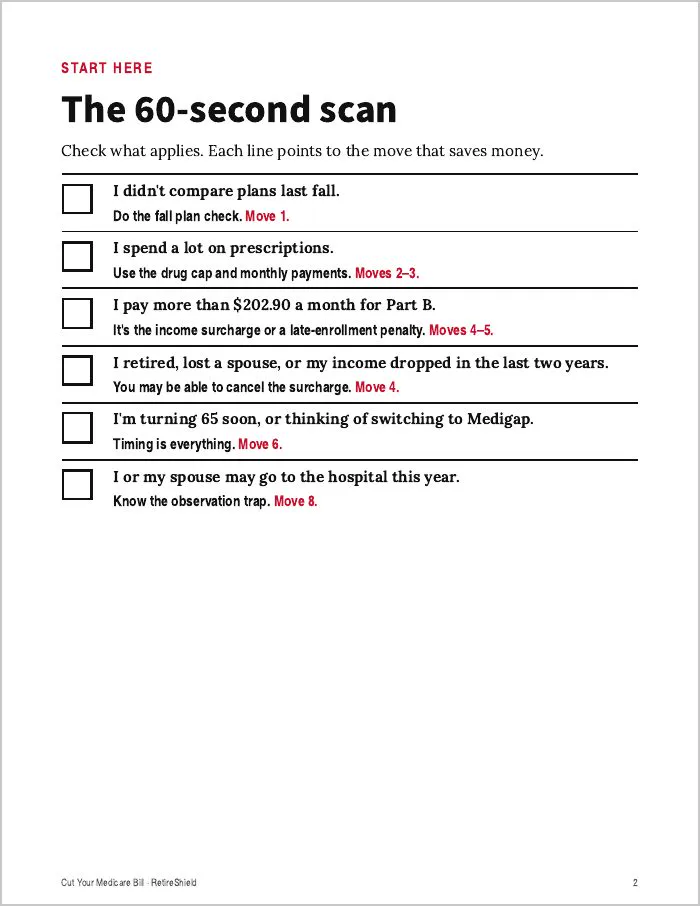
The 60-second scan
Tick what applies. Each line points to the move that saves money.
What to do, step by step
The forms, the dates, and the questions to ask.
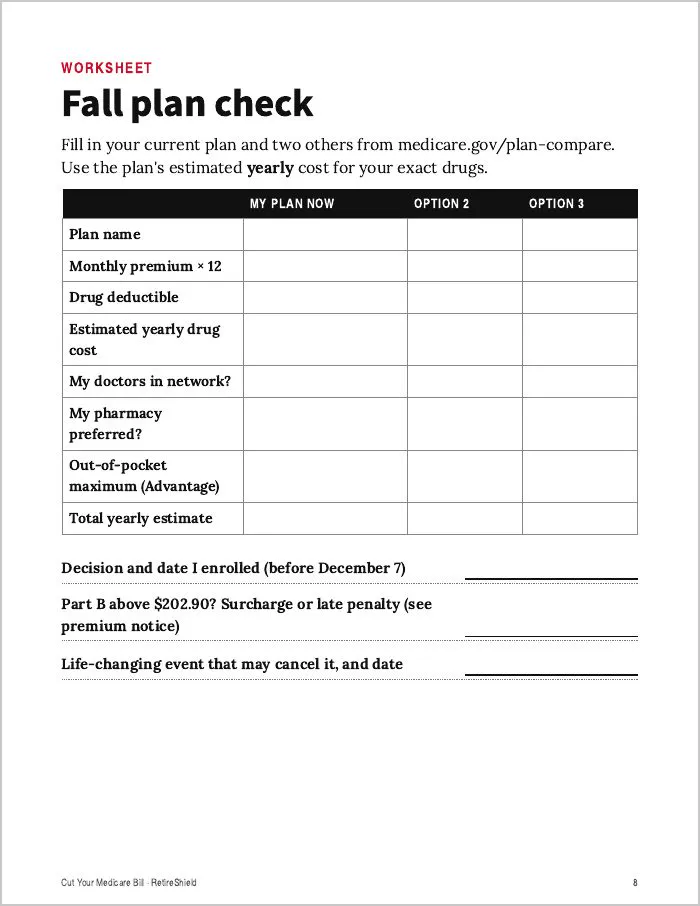
Fall plan check
Your plan and two others side by side, with the total yearly cost.
CMS, Medicare.gov and SSA
Checked October 2026, every link listed.
Large-print and audio editions
The same guide in big type, and read aloud (about 10 minutes). Listen on any phone, tablet or computer.
Look inside
Real pages from the guide.
How it works
Cut Your Medicare Bill
Card, Apple Pay or PayPal · secure checkout
Instant download, large print and audio included, 30-day money-back promise.
PROMISE
Read it. Use it. If it isn't for you, get every penny back.
Email us within 30 days for a full refund. You keep the files.
Questions
Why is my Part B premium more than $202.90?
It's one of two things: the income surcharge, or a late-enrollment penalty for signing up for Part B late. Your Social Security premium notice says which. Only the surcharge can be appealed with Form SSA-44, and the guide shows how.
Will you tell me which plan to pick?
No. The guide shows how to compare plans on medicare.gov for your exact drugs and pharmacy. For free one-on-one help from someone who isn't selling a plan, it points you to your state's SHIP counselors.
When do I get it?
Immediately. The download appears on your screen the moment you pay, and a copy is emailed to you at once.
Is this a subscription?
No. It's one payment. There is nothing recurring and nothing to cancel.
Is it easy to read?
Yes. Plain English, short sections, and large-print and audio editions are included. It opens on any phone, tablet or computer, and prints cleanly.
What if it's not for me?
Email us within 30 days for a full refund. Keep the files.
RetireShield is independent and is not affiliated with, endorsed by, or connected to Medicare, CMS, Social Security or any government agency. This product provides educational information, not insurance, medical, financial or legal advice.
Pay less for the same care. $27.
Instant download, large print and audio included, 30-day money-back promise.
Get the guide — $27