Keep-It Step 5 · 2026–2027 Edition
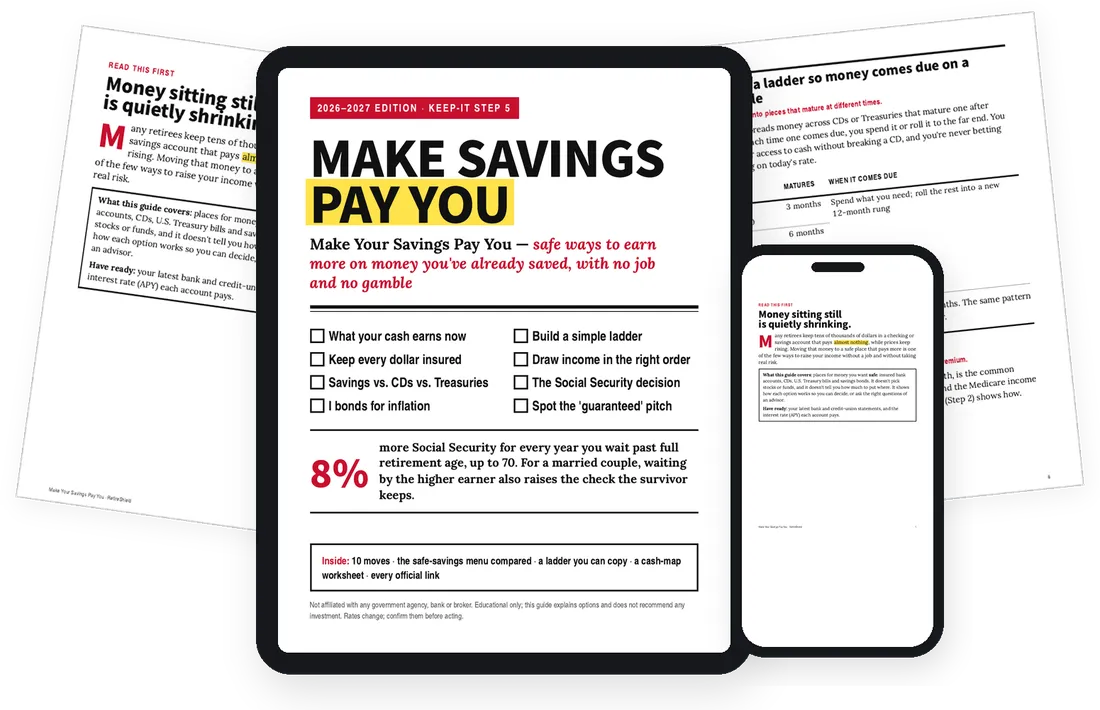
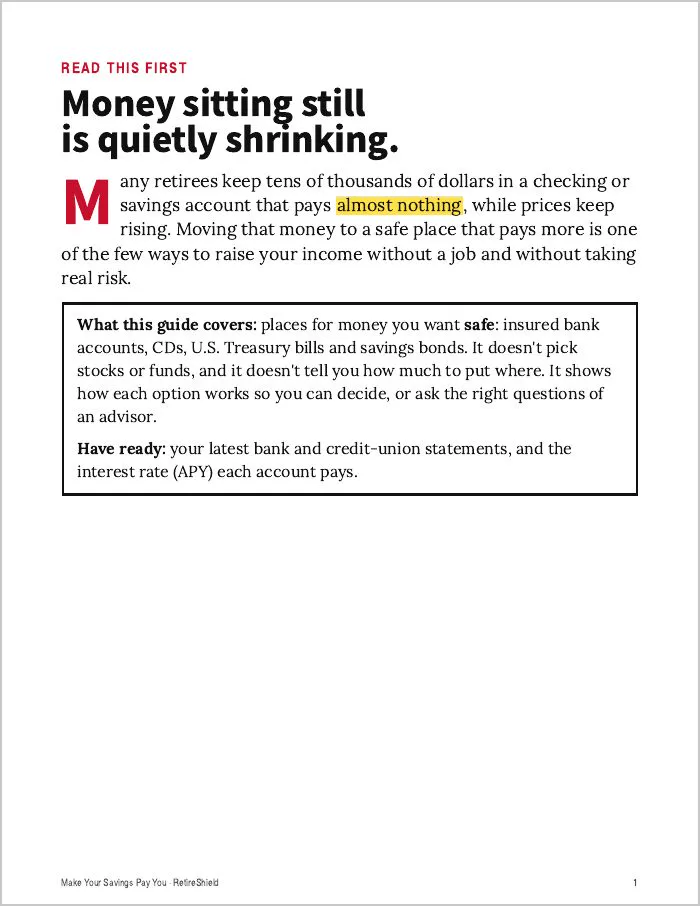
Money sitting still is quietly shrinking. Here's how to make your savings pay you.
Many retirees keep tens of thousands of dollars in an account that pays almost nothing, while prices keep rising. This guide shows the safe places that pay more: insured bank accounts, CDs, Treasury bills and savings bonds. No job and no gamble.
Sound familiar?
Your savings may be earning almost nothing while prices keep rising.
Many big-bank savings and checking accounts pay a tiny fraction of a percent. Insured high-yield accounts and Treasury bills have paid several percent. On $50,000, that gap is about $1,950 a year.
- Not sure what rate your savings earns
- More than $250,000 at one bank
- Worried about prices going up
- Someone offered you a "guaranteed" high return
What you get
Ten moves to earn more on money you've already saved.
- What your cash earns now, found on your statement in five minutes
- Every dollar insured, even above $250,000 at one bank
- High-yield savings for the cushion you might need this year
- CDs for money you won't touch for a while, and the penalty to read first
- Treasury bills from $100, free of state and local income tax
- I bonds whose rate adjusts with inflation every six months
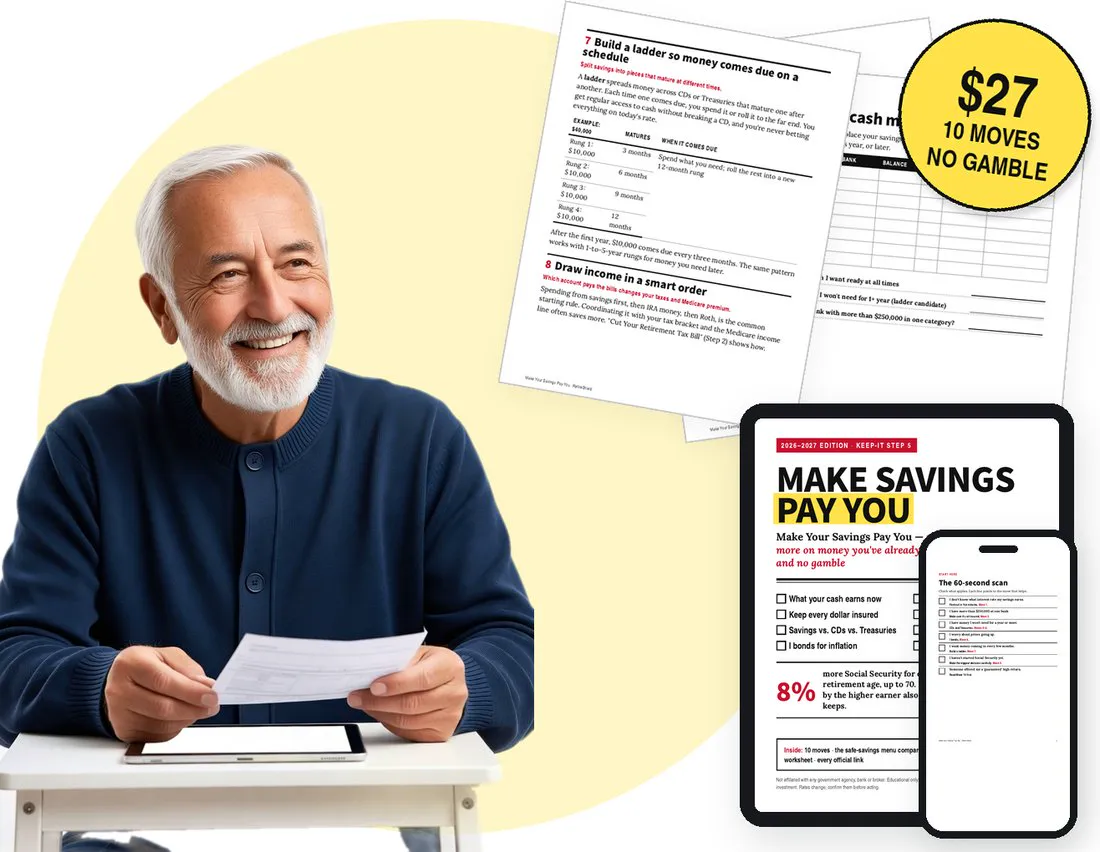
- A ladder so money comes due on a schedule
- The Social Security decision: 8% more for each year you wait past full retirement age, up to 70
What's inside
What's in the guide.
What this guide covers
Places for money you want safe, and how each one works.
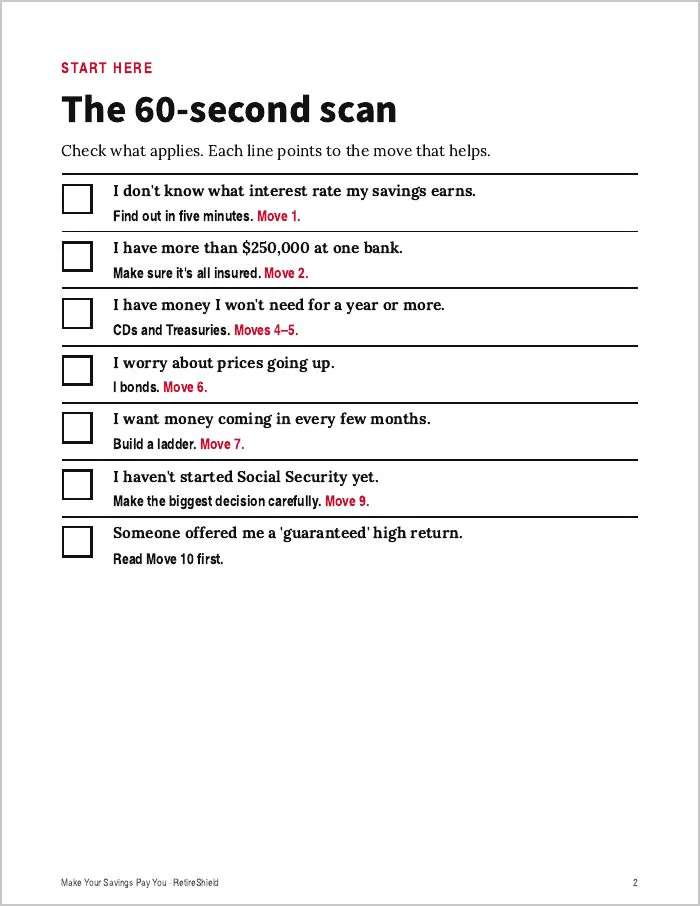
The 60-second scan
Tick what applies. Each line points to the move that helps.
The safe-savings menu
Savings accounts, CDs, Treasury bills and I bonds, compared.
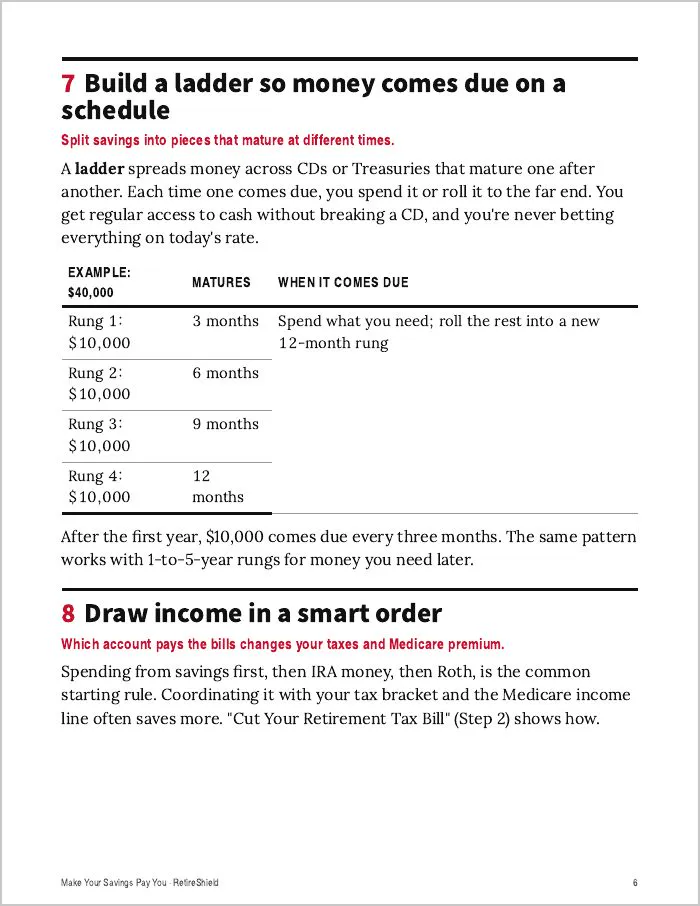
A ladder you can copy
$40,000 in four rungs. After the first year, $10,000 comes due every three months.
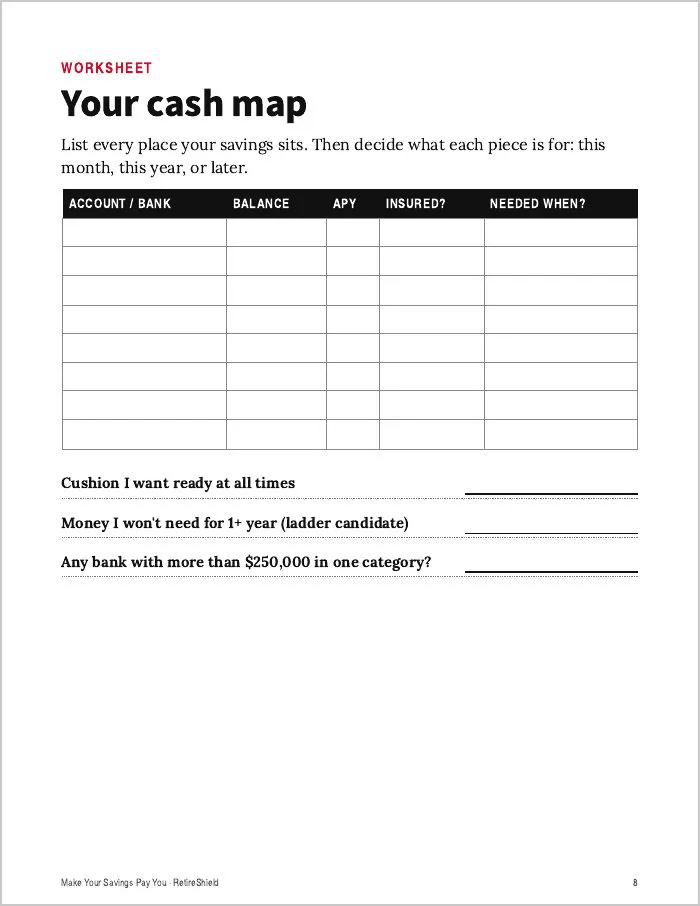
Your cash map
Every account, its balance, its rate, and when you'll need it.
Large-print and audio editions
The same guide in big type, and read aloud (about 9 minutes). Listen on any phone, tablet or computer.
Look inside
Real pages from the guide.
How it works
Make Your Savings Pay You
Card, Apple Pay or PayPal · secure checkout
Instant download, large print and audio included, 30-day money-back promise.
PROMISE
Read it. Use it. If it isn't for you, get every penny back.
Email us within 30 days for a full refund. You keep the files.
Questions
Will it tell me what to invest in?
No. It explains how each safe option works so you can decide, or ask the right questions of an advisor. It doesn't pick stocks or funds, and it doesn't tell you how much to put where.
How do I know my money is insured?
The FDIC insures bank deposits up to $250,000 per person, per bank, for each ownership category. Credit unions have the same limit through the NCUA. The guide also lists what isn't insured, like money market mutual funds and annuities, even when you buy them at a bank.
When do I get it?
Immediately. The download appears on your screen the moment you pay, and a copy is emailed to you at once.
Is this a subscription?
No. It's one payment. There is nothing recurring and nothing to cancel.
Is it easy to read?
Yes. Plain English, short sections, and large-print and audio editions are included. It opens on any phone, tablet or computer, and prints cleanly.
What if it's not for me?
Email us within 30 days for a full refund. Keep the files.
RetireShield is independent and is not affiliated with, endorsed by, or connected to any government agency, bank or broker. This product provides educational information, not financial, tax, legal or investment advice. It explains options and does not recommend any investment.
Make your savings pay you. $27.
Instant download, large print and audio included, 30-day money-back promise.
Get the guide — $27