Keep-It Step 2 · 2026–2027 Edition
A few income lines decide your tax bill every year. Here's how to stay on the right side of each.
The line where Social Security starts being taxed. The bracket lines. The line where Medicare adds a surcharge. The age when the IRS forces withdrawals. Cross one by accident and you pay more every year. This guide shows each line in 2026 numbers, with 12 moves to plan around them.
Sound familiar?
Every cost-of-living raise pushes more retirees over the line.
The income lines that decide whether your Social Security is taxed are written into the law and have never been raised for inflation. Medicare's surcharge uses your tax return from two years ago. One large withdrawal at the wrong time can raise both bills.
- Paying tax on Social Security you could have kept
- A new senior deduction missing from your return
- A one-time sale that raised your Medicare premium two years later
- Two RMDs in one year, and a higher bracket
What you get
Twelve moves. Read only the ones that fit you.
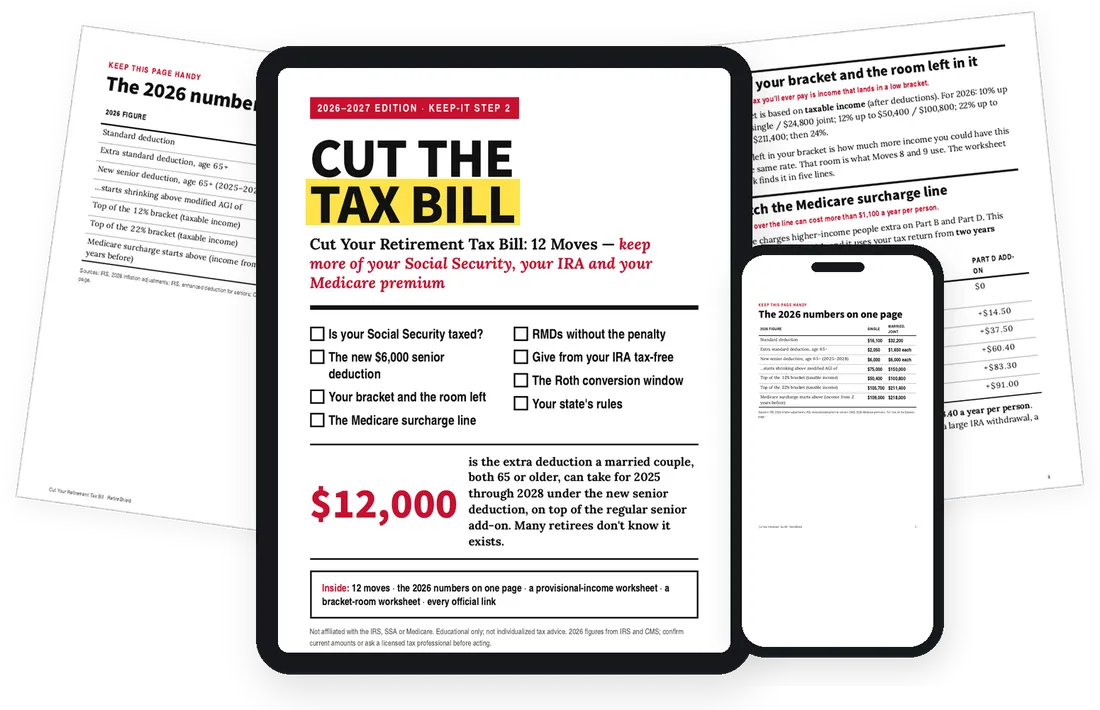
- The new $6,000 senior deduction, $12,000 for a couple, for 2025 through 2028
- The regular senior add-on that stacks on top of it
- How much of your Social Security is taxed, worked out on one worksheet
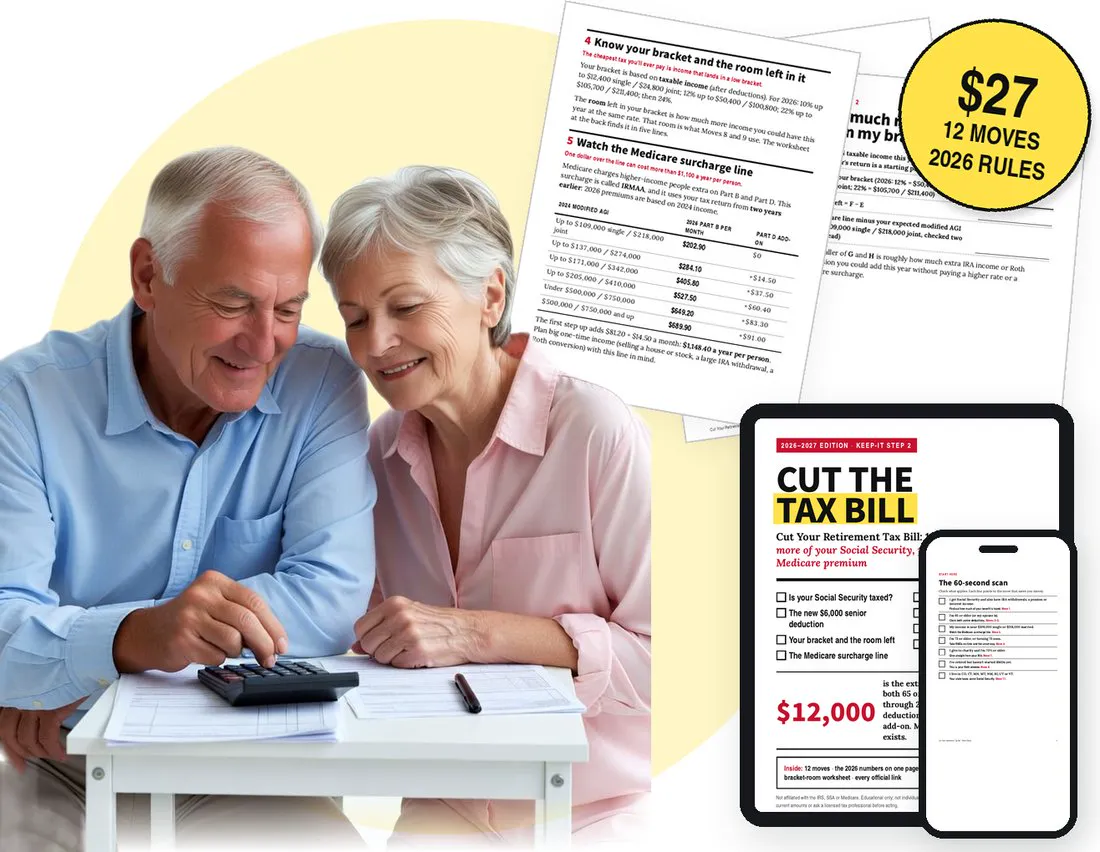
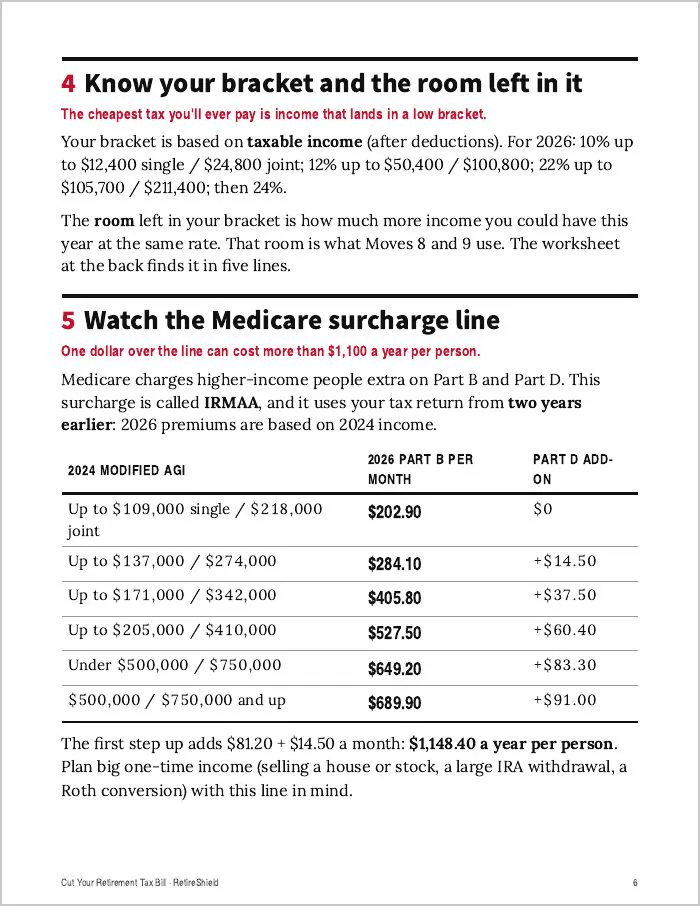
- The Medicare surcharge line, where one dollar over can cost more than $1,100 a year per person
- RMDs on time, without the 25% penalty or the first-year trap
- Giving from your IRA straight to charity, left out of your taxable income
- The Roth window between retiring and your first RMD
- Your state's rules, including the eight states that tax some Social Security
What's inside
What's in the guide.
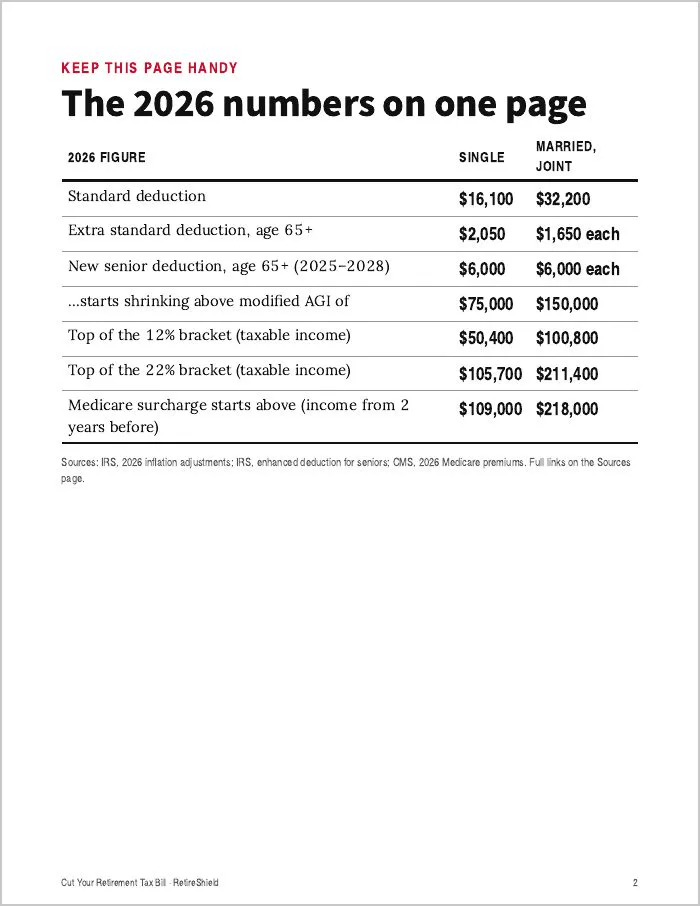
The 2026 numbers on one page
Deductions, brackets and the Medicare line, single and married.
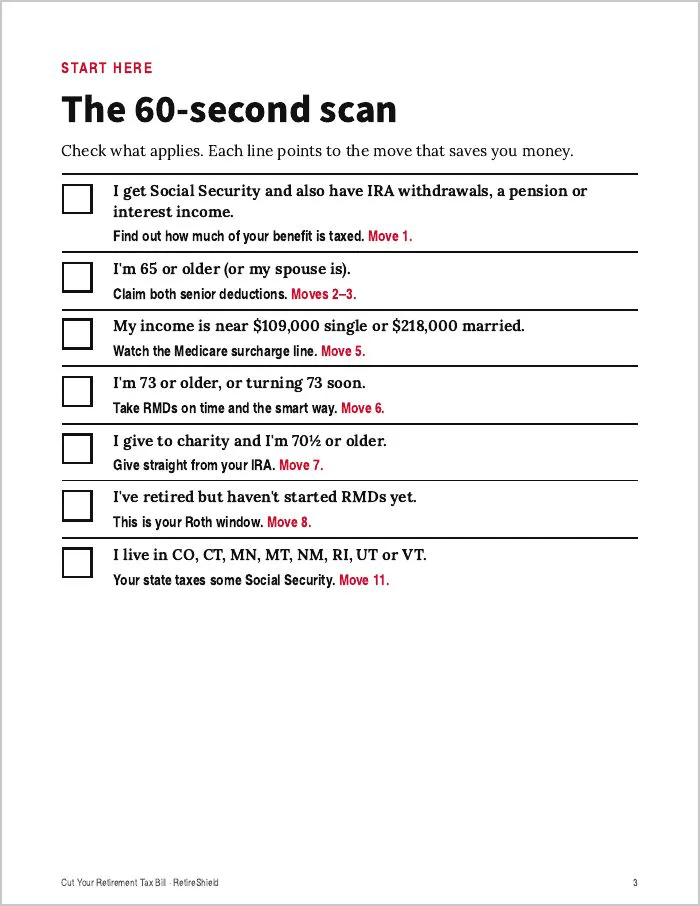
The 60-second scan
Tick what applies. Each line points to the move that saves you money.
What to do, and the form to use
Schedule 1-A, Form 5329, Form W-4V and more, with official links.
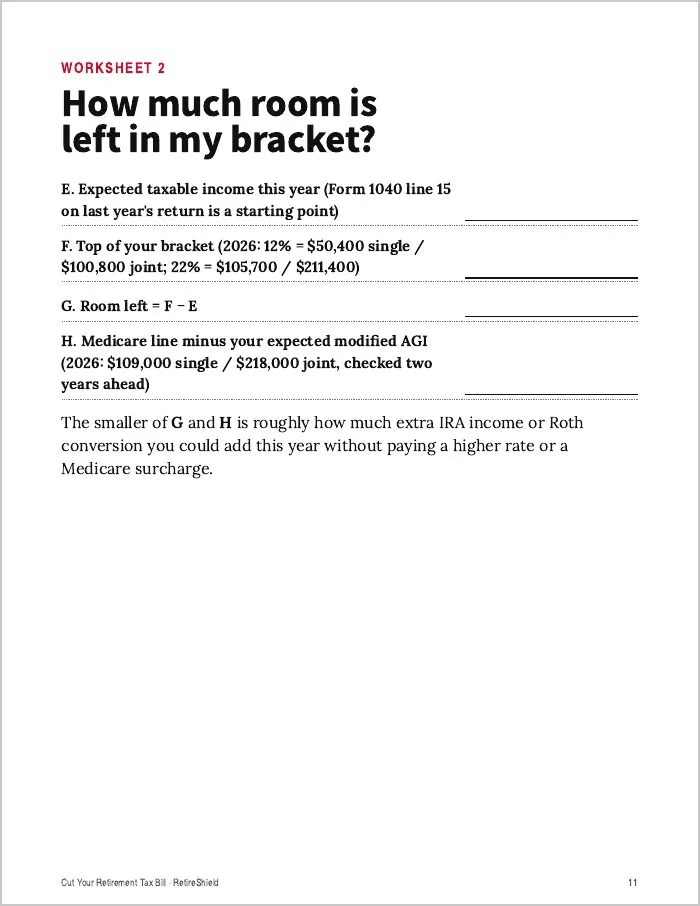
Two worksheets that do the math
Is my Social Security taxed? How much room is left in my bracket?
IRS, SSA and CMS
Checked October 2026, every link listed.
Large-print and audio editions
The same guide in big type, and read aloud (about 17 minutes). Listen on any phone, tablet or computer.
Look inside
Real pages from the guide.
How it works
Cut Your Retirement Tax Bill: 12 Moves
Card, Apple Pay or PayPal · secure checkout
Instant download, large print and audio included, 30-day money-back promise.
PROMISE
Read it. Use it. If it isn't for you, get every penny back.
Email us within 30 days for a full refund. You keep the files.
Questions
Do I have to itemize to get the new senior deduction?
No. It's available whether you itemize or take the standard deduction. It's claimed on Schedule 1-A of Form 1040, and it starts shrinking above $75,000 of income for one person or $150,000 for a married couple filing jointly.
What should I have ready?
Last year's tax return (Form 1040), your Social Security benefit statement (Form SSA-1099), and the year-end statements for your IRA, 401(k) and bank accounts.
When do I get it?
Immediately. The download appears on your screen the moment you pay, and a copy is emailed to you at once.
Is this a subscription?
No. It's one payment. There is nothing recurring and nothing to cancel.
Is it easy to read?
Yes. Plain English, short sections, and large-print and audio editions are included. It opens on any phone, tablet or computer, and prints cleanly.
What if it's not for me?
Email us within 30 days for a full refund. Keep the files.
RetireShield is independent and is not affiliated with, endorsed by, or connected to the IRS, Social Security, Medicare or any government agency. This product provides educational information, not tax, legal, financial or investment advice.
Keep more of what you've saved. $27.
Instant download, large print and audio included, 30-day money-back promise.
Get the guide — $27