Wait to claim and your check grows. The gap can be $1,134 a month, for life.
A simple kit. It shows what each age pays you. It finds the age where waiting pays off. It shows how to add spouse and widow checks. A calculator does the math.
- Start Here: 62, 67, or 70?
- The Claiming Calendar and Worksheets
- Part 1 — How Your Number Is Set
- Part 2 — The Age Decision: What Waiting Is Worth
- Part 3 — Still Working? The Earnings Test
- Part 4 — Spousal and Divorced-Spouse Benefits
- Part 5 — Survivor Benefits and the Switch
- Part 6 — Already Claimed? Two Ways Back
- Part 7 — Pensions, Remarriage and Family Benefits
- The 5-Tab Claiming Calculator (Excel)
- Claiming Quick-Start (Large Print)
- SSA Appointment, Records & Evidence Pack
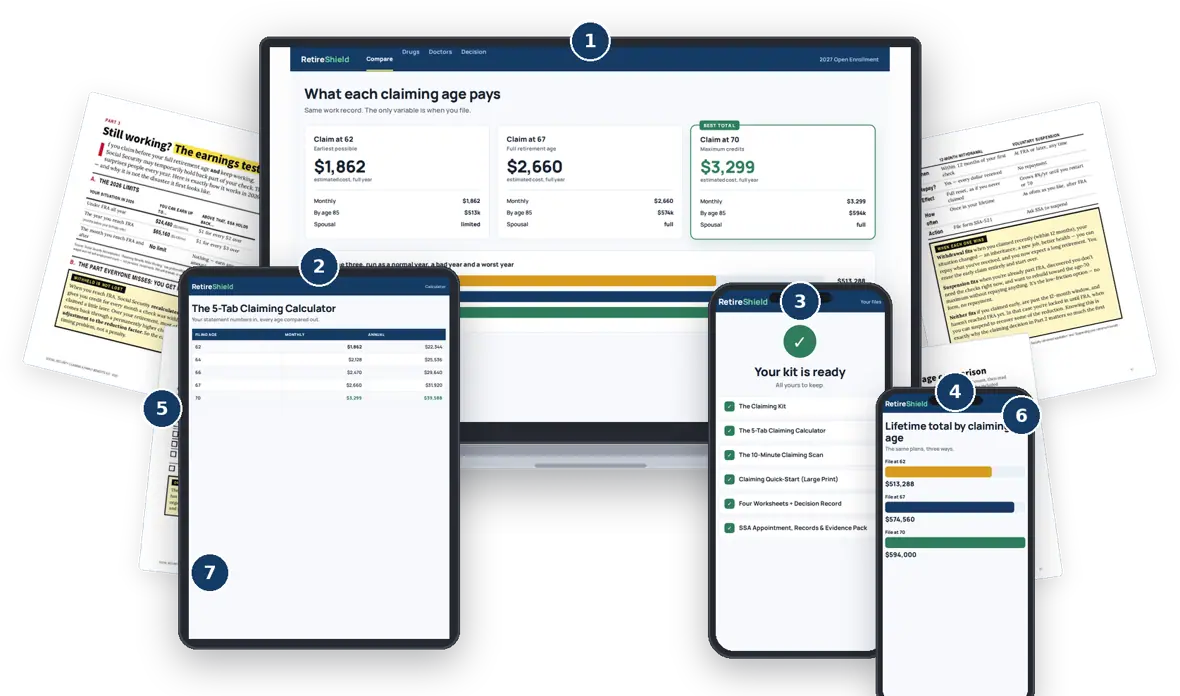
Delayed retirement credits and the early-claiming reduction: SSA. Example: $2,100 at full retirement age 67 is $1,470 at 62 and $2,604 at 70. Your own gap depends on your record — the calculator works it out from your statement.
Right now you might be thinking…
Sound familiar?
Every one of those is covered in here. This was built for people starting from exactly that spot.
By the end of it, you can…
- ✓See what your check is at 62, at full age, and at 70. From your own SSA letter.
- ✓Find your break-even age in minutes. Then you know which age pays more.
- ✓Know the 2026 work limits if you still have a job. And when held-back money comes back to you.
- ✓Add spouse, ex-spouse, and widow checks in the right order. Most people miss one switch.
- ✓Use the rules that can save a bad choice. The 12-month do-over. And the pause up to age 70.
…and a good deal more.
I WANT IT ALL — $57All 11 parts · instant access↓ Keep scrolling for all 11 parts ↓
If you want to be sure of the answer, these six do that:
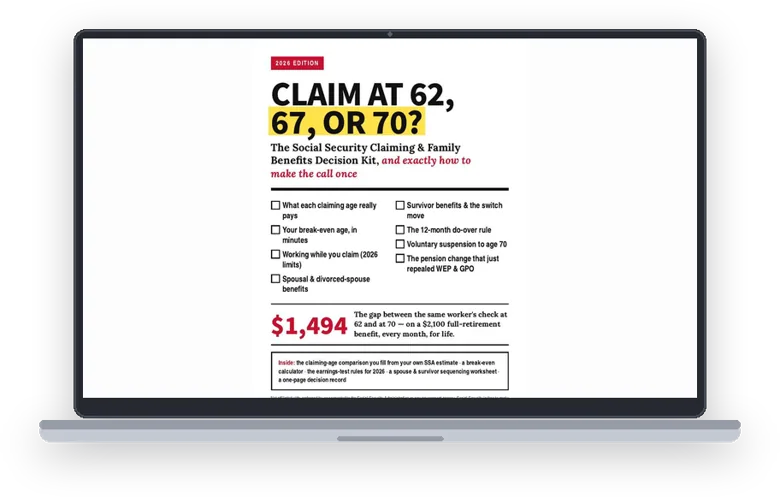
Start Here: 62, 67, or 70?
The decision laid out on three pages, with the number that frames it: on a $2,100 full-retirement benefit, the gap between claiming at 62 and at 70 is $1,134 a month, for life. Read this, then go straight to the part that fits your situation.
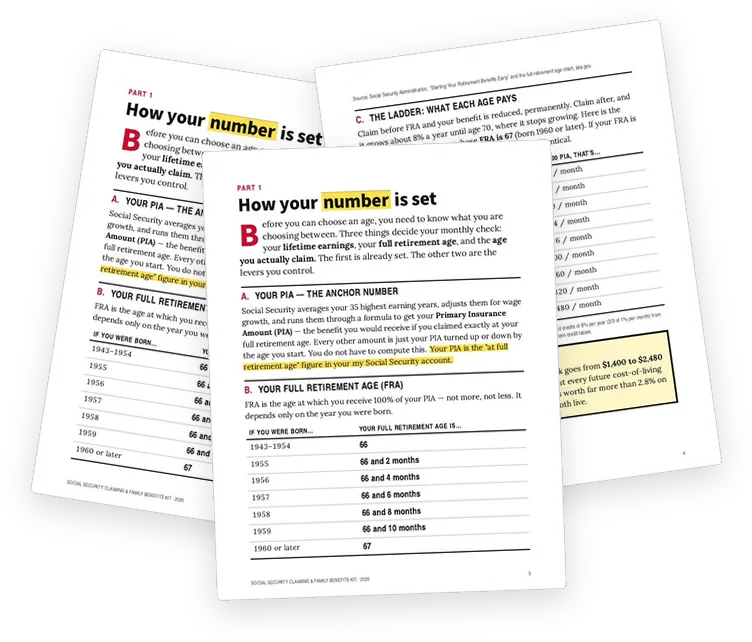
Part 1 · How Your Number Is Set
Before you can pick an age you need to know what you are choosing between. Your PIA, how SSA builds it from your 35 highest earning years, your full retirement age, and which of the three levers is already fixed and which two you still control.
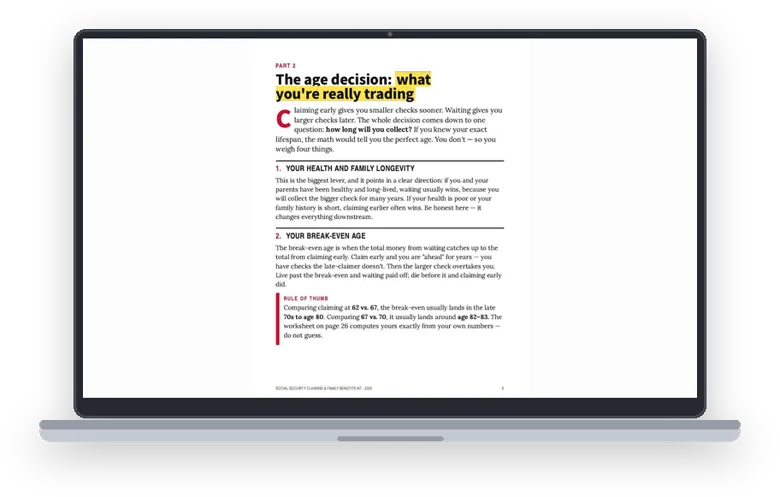
Part 2 · The Age Decision: What Waiting Is Worth
Claiming early means smaller checks sooner. The whole thing comes down to how long you collect — and since nobody knows that, you weigh four things instead. Health and family longevity, whether you are still working, your savings, and whether you are the higher earner in a marriage.
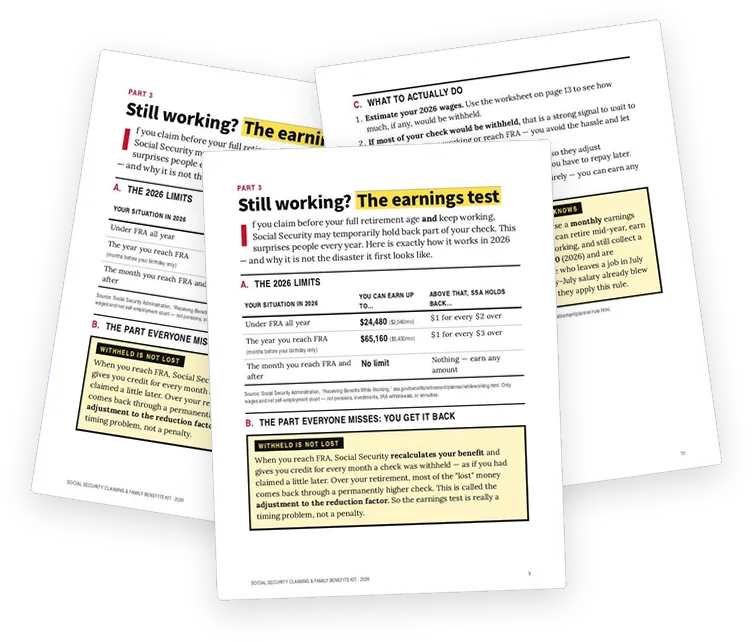
Part 3 · Still Working? The Earnings Test
Claim before full retirement age and keep working, and SSA may hold part of your check back. The 2026 limits, the $1-for-$2 and $1-for-$3 rules, the month the limit disappears entirely — and why the money held back is not actually lost.
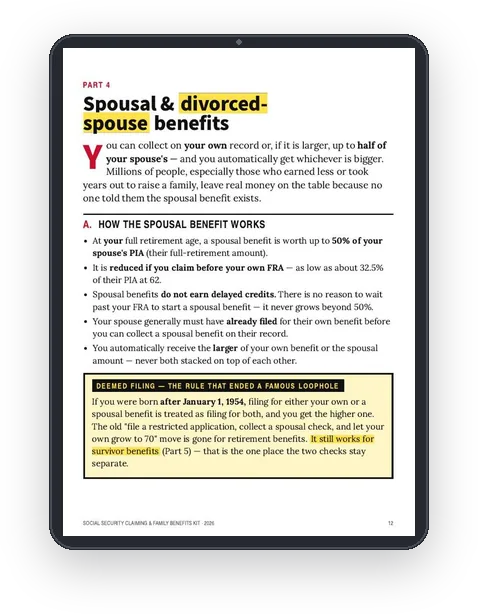
Part 4 · Spousal and Divorced-Spouse Benefits
Up to half of your spouse's full-retirement amount, and you automatically get whichever is larger. Including the rule most people have never heard: a marriage that lasted ten years still counts after a divorce, and your ex is never told you claimed.
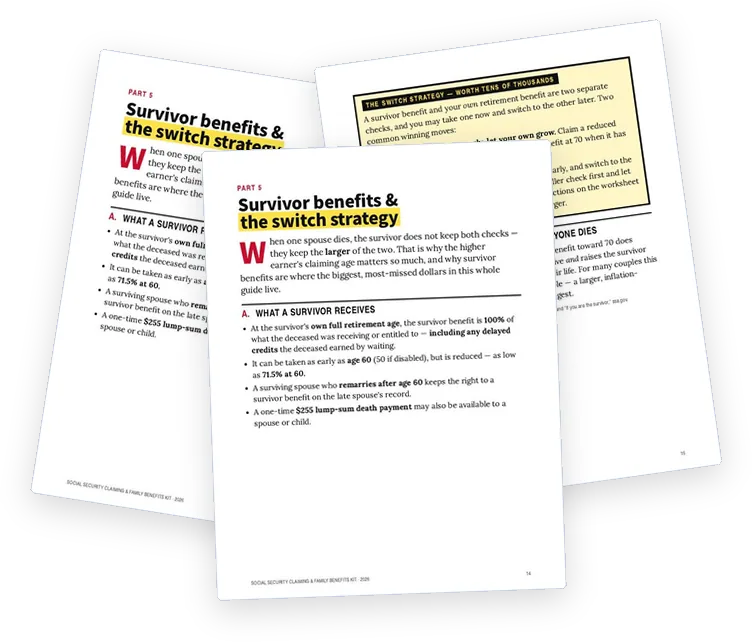
Part 5 · Survivor Benefits and the Switch
When one spouse dies the survivor keeps the larger check, not both. That one sentence is why the higher earner's claiming age matters so much, and this is where the biggest missed dollars in the whole kit live.
If you want it to hold, these do that:
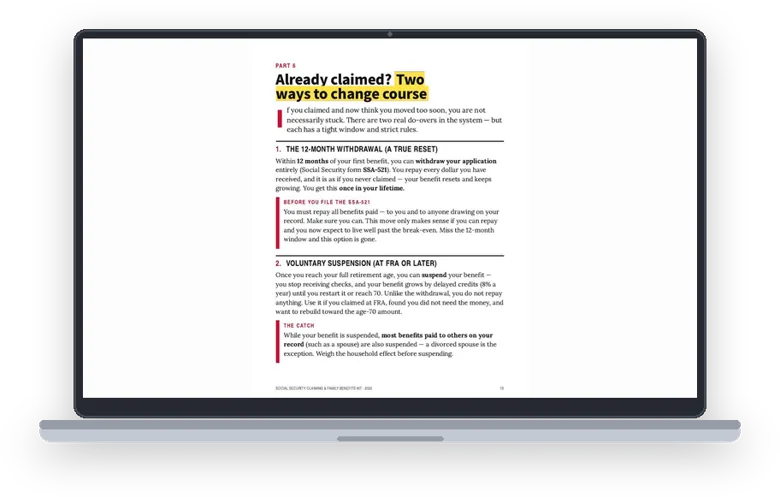
Part 6 · Already Claimed? Two Ways Back
If you moved too soon you are not necessarily stuck. The 12-month withdrawal that resets your benefit completely, and the voluntary suspension that restarts the increases at full retirement age — with the repayment rules and the tight windows on each.
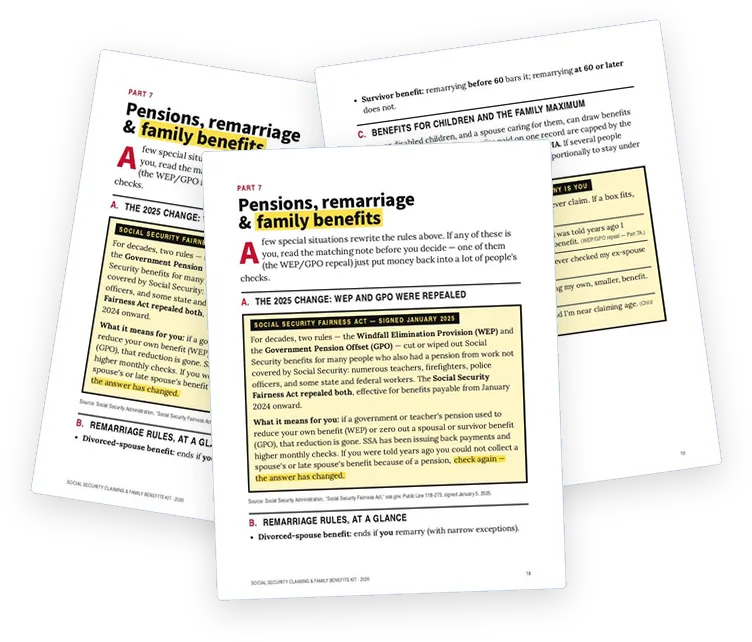
Part 7 · Pensions, Remarriage and Family Benefits
The special situations that rewrite everything above, starting with the 2025 repeal of WEP and GPO that put money back into many government and teacher pension households. Plus remarriage rules, children's benefits, and the family maximum.
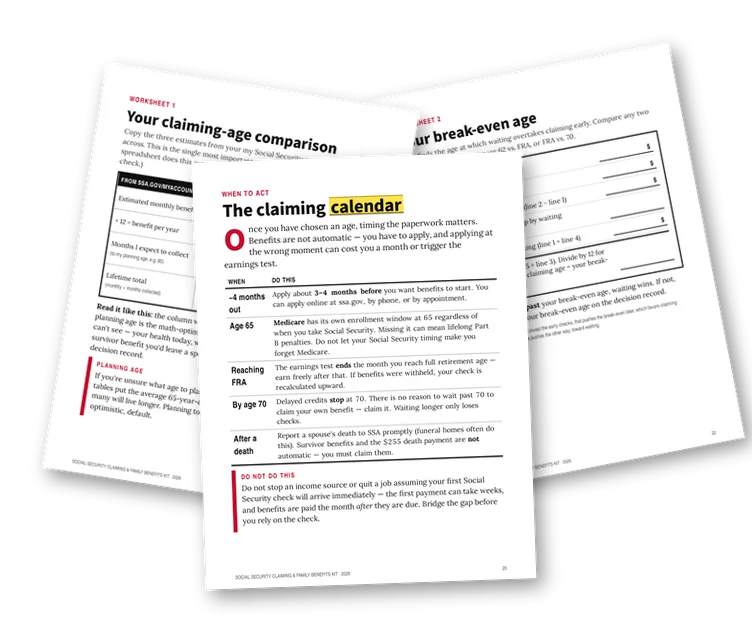
The Claiming Calendar and Worksheets
The claiming calendar, then four worksheets: your claiming-age comparison, your break-even age, spouse and survivor sequencing, and the one-page decision record. Plus what to have ready when you apply, and the sources.
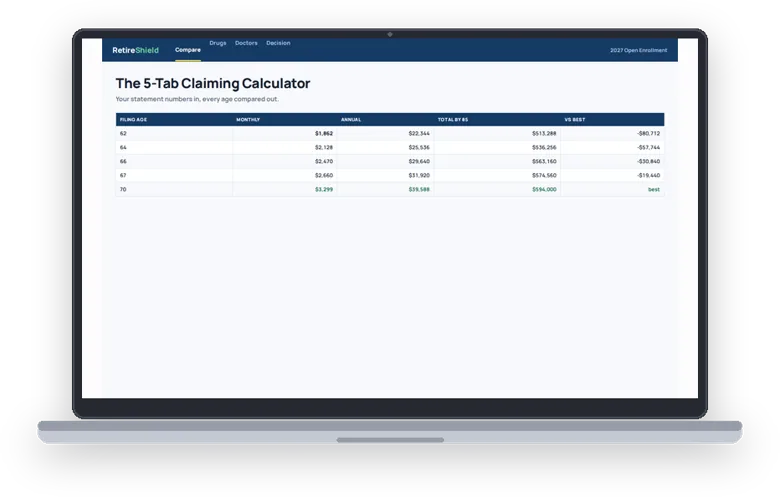
The 5-Tab Claiming Calculator (Excel)
You type in the three estimates from your own SSA statement. It returns your monthly amount at every age from 62 to 70, your break-even age, the spousal and survivor figures, and the lifetime totals side by side.
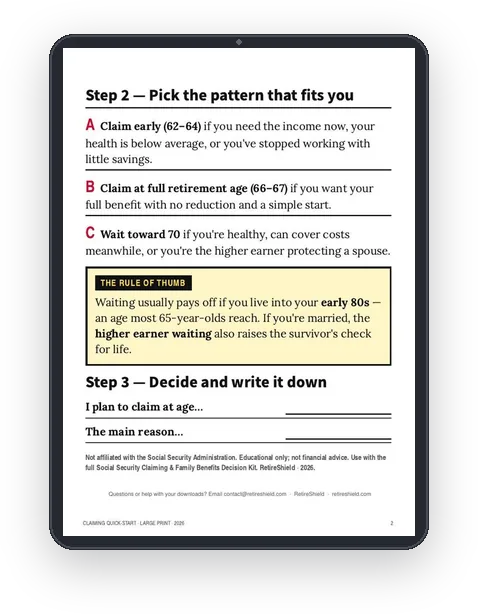
Claiming Quick-Start (Large Print)
Two large-print pages: the three patterns most people fall into, the rule of thumb on who should wait, and a line to write down your decision and the reason for it.
Add it up:
You save $205. That is 78% off.
GET INSTANT ACCESS — $57All 11 parts · instant accessFrom people who bought it
Here is what a few have said ↓
“Instead of just explaining Social Security, it helped me compare different claiming ages and write down the numbers. My wife and I were finally able to sit down and discuss what we actually wanted to do.”
“I probably could have found most of this information eventually, but I would have spent days doing it. This organized it into one system and showed me what information mattered.”
“My parents are in their 70s and I handle a lot of their paperwork. The checklists made it much easier to figure out what had already been handled and what still needed attention.”
“I've bought retirement PDFs before that were basically blog posts turned into downloads. This actually had worksheets, calculators, checklists, examples, and specific resources.”
Reviews are from RetireShield customers, and cover our kits as a whole rather than this one alone. Individual results. Results may vary and are not guaranteed.
The usual hesitations:
“Everybody says take it as soon as you can”
That is right for some people and costly for others. Part 2 weighs what decides it for you: your health, whether you still work, your savings, and more.
“I do not understand my statement”
Part 1 explains the numbers on your SSA statement, and the calculator turns them into your monthly amount at every age from 62 to 70.
“I did not know my spouse mattered to this”
Most people do not. Parts 4 and 5 cover spouse and survivor checks, and why the higher earner's claiming age matters most.
“I already claimed. It is too late”
Not always. Part 6 covers the 12-month do-over and the pause at full retirement age.
30 days. You risk nothing.
If it does not help you, email us inside 30 days and we send back every penny. We will not ask you why. We never sell your name or your email.
The practical questions
Is this easy to use?+
Yes. Plain words, big type, short parts. The calculator asks for a few numbers. If you can read a letter and use a simple spreadsheet, you can use this.
Do I need my SSA letter?+
It helps. Get yours free at ssa.gov under my Social Security. The kit shows which numbers to type in. You can also start with the sample numbers in the guide.
Do I need Excel?+
The calculator opens in Excel, Numbers, or free Google Sheets. The rest are PDFs. They open on any device.
When do I get it?+
Right away. It shows up on your screen the moment you pay. We email you a copy too.
Do I pay every month?+
No. You pay $57 one time. Nothing repeats. There is nothing to cancel.
Is this money advice?+
No. It is a guide and a calculator. Social Security is free to sign up for at ssa.gov or 1-800-772-1213. You always file with SSA yourself.
Wait to claim and your check grows. The gap can be $1,134 a month, for life.
- Start Here: 62, 67, or 70?
- The Claiming Calendar and Worksheets
- Part 1 — How Your Number Is Set
- Part 2 — The Age Decision: What Waiting Is Worth
- Part 3 — Still Working? The Earnings Test
- Part 4 — Spousal and Divorced-Spouse Benefits
- Part 5 — Survivor Benefits and the Switch
- Part 6 — Already Claimed? Two Ways Back
- Part 7 — Pensions, Remarriage and Family Benefits
- The 5-Tab Claiming Calculator (Excel)
- Claiming Quick-Start (Large Print)
- SSA Appointment, Records & Evidence Pack
Takes about a minute. You will be reading in two.
The Retirement Money Brief
Our free email for people over 65. One change to Medicare, taxes or benefits each weekday morning — the date to watch, and the one step to take.
RetireShield is independent and is not affiliated with or endorsed by any government agency. Our materials are educational and are not legal, tax, medical, insurance or benefits advice. Results may vary and are not guaranteed. © 2026 RetireShield.