RetireShield Medicare Guide · 2026–2027 Edition
It's the Medicare choice that's hardest to undo. Know your rights before you sign anything.
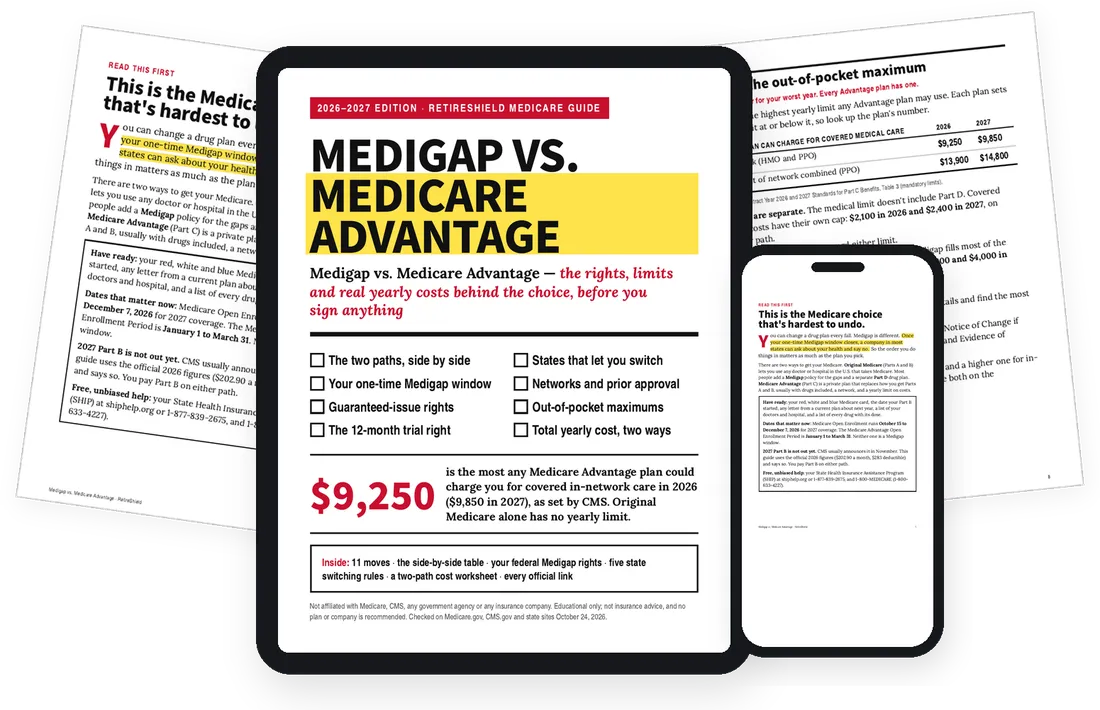
Original Medicare with Medigap, or a Medicare Advantage plan? You can change a drug plan every fall. Medigap is different: once your one-time window closes, a company in most states can ask about your health and say no. This guide puts both paths side by side, lists your federal rights, and shows how to price a routine year and a bad year.
Sound familiar?
A $0 plan sounds simple. Getting back out can be the hard part.
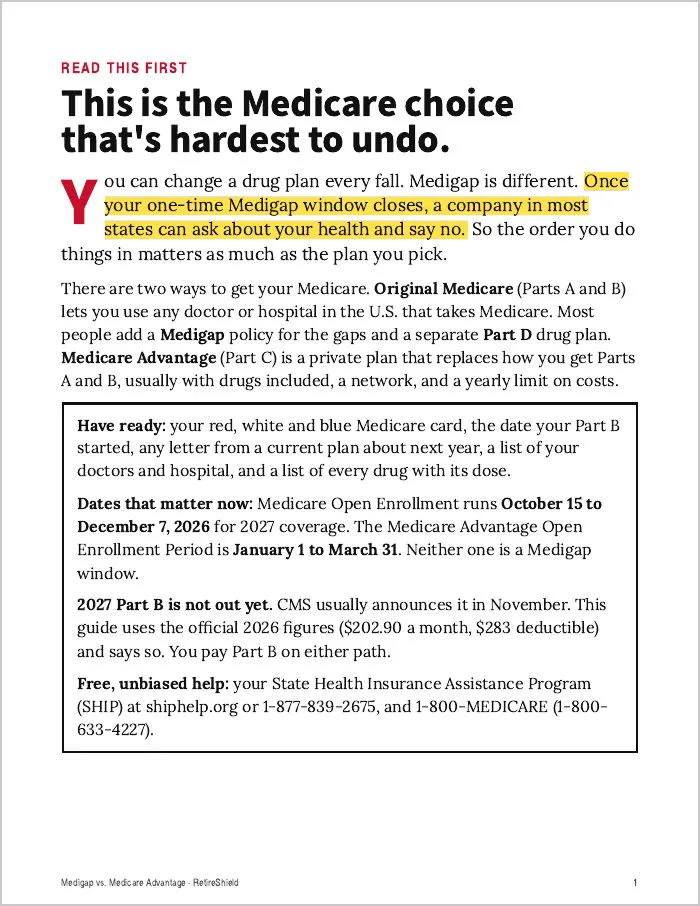
You can change a drug plan every fall. Medigap works differently. After your one-time window, a company in most states can ask about your health and say no. So the order you do things in matters as much as the plan you pick.
- Someone calling you about a "$0 plan"
- Only ever compared monthly premiums
- Not sure your doctors are in the network
- Thinking of leaving Advantage without knowing your rights
What you get
Eleven moves. Know your rights first. Then compare.
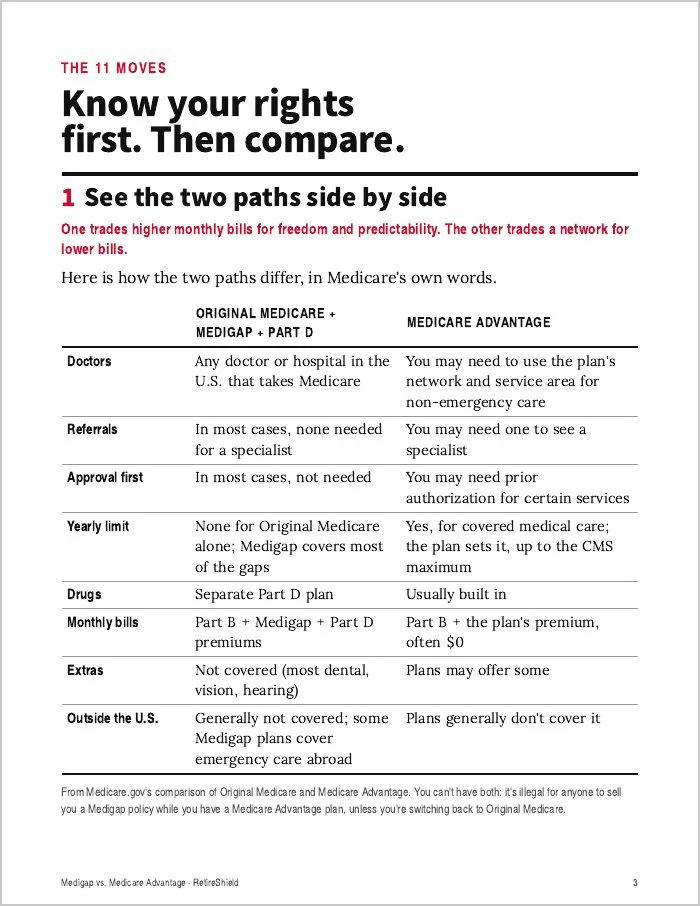
- The two paths side by side: doctors, referrals, approvals, yearly limits and drugs, in Medicare's own words
- Your one-time Medigap window: 6 months, starting the first month you have Part B and are 65 or older
- Guaranteed-issue rights: the federal situations where a company can't turn you down for your health
- The trial right if you're within your first year on Medicare Advantage
- Five state switching rules: New York, California, Oregon, Illinois and Missouri
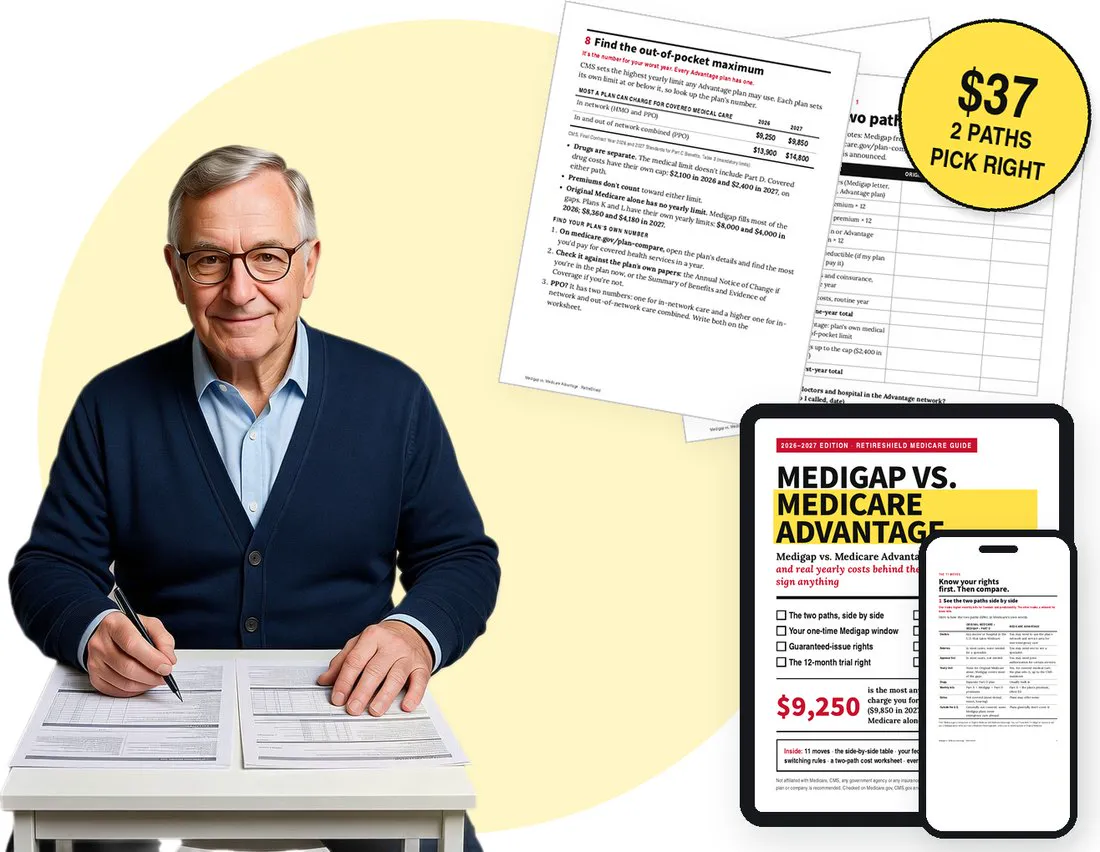
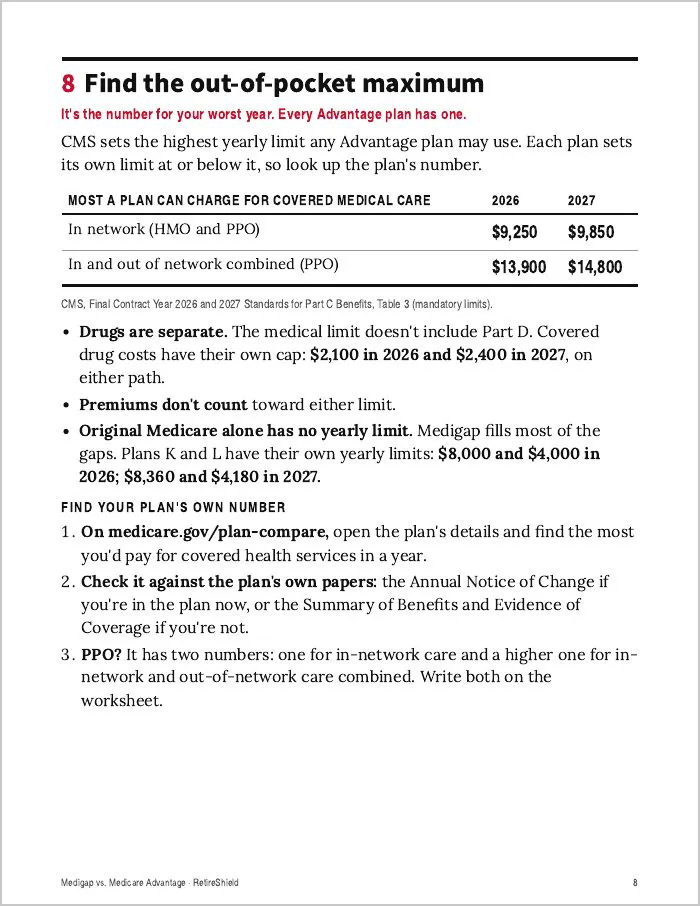
- The out-of-pocket maximum: $9,250 in network in 2026 and $9,850 in 2027, the most any Advantage plan may set
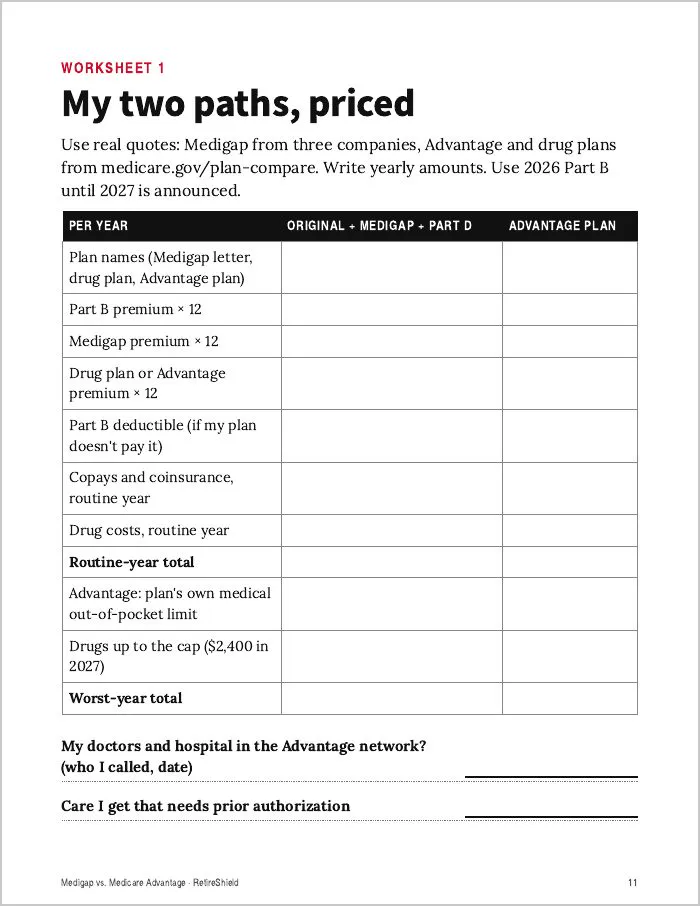
- Total yearly cost, two ways: price a routine year and your worst year
- Switch in the right order: new coverage approved in writing before you drop the old
What's inside
What's in the guide.
The choice that's hardest to undo
The two paths, the dates that matter now, and what to have ready.
The 60-second scan
Tick what applies. Each line points to the move that fits it.
Your rights, then the comparison
Medigap windows, state rules, networks, prior approval and yearly limits.
Your two paths, priced
Your own quotes side by side, plus your Medigap dates and deadlines.
Medicare.gov, CMS and state sites
Checked October 24, 2026, every link listed.
Large-print and audio editions
The same guide in big type, and read aloud (about 21 minutes). Listen on any phone, tablet or computer.
Look inside
Real pages from the guide.
How it works
Medigap vs. Medicare Advantage
Card, Apple Pay or PayPal · secure checkout
Instant download, large print and audio included, 30-day money-back promise.
PROMISE
Read it. Use it. If it isn't for you, get every penny back.
Email us within 30 days for a full refund. You keep the files.
Questions
Will you tell me which path or plan to pick?
No. The guide doesn't name or recommend any plan or company. It shows the rules and how to price both paths with your own quotes. For free one-on-one help from someone who isn't selling a plan, it points you to your State Health Insurance Assistance Program (SHIP) and 1-800-MEDICARE.
Is Open Enrollment my chance to get Medigap?
Not on its own. Open Enrollment (October 15 to December 7) and the January 1 to March 31 Advantage period are not Medigap windows. Outside your one-time window, a company in most states can use your health to decide, unless you have a guaranteed-issue right, a trial right or a state rule. The guide shows how to check which applies to you.
Are the 2027 numbers in it?
Yes, where they're published: the 2027 Advantage out-of-pocket limits, the $2,400 drug cap for 2027, and the 2027 amounts for Medigap Plans K and L and high-deductible Plan G. The 2027 Part B premium isn't out yet. CMS usually announces it in November, so the guide uses the 2026 figures ($202.90 a month, $283 deductible) and labels them.
When do I get it?
Immediately. The download appears on your screen the moment you pay, and a copy is emailed to you at once.
Is this a subscription?
No. It's one payment. There is nothing recurring and nothing to cancel.
Is it easy to read?
Yes. Plain English, short sections, and large-print and audio editions are included. It opens on any phone, tablet or computer, and prints cleanly.
What if it's not for me?
Email us within 30 days for a full refund. Keep the files.
RetireShield is independent and is not affiliated with, endorsed by, or connected to Medicare, CMS, Social Security, any government agency or any insurance company. This product provides educational information, not insurance, medical, financial or legal advice. No plan or company is recommended.
Know your rights before you choose. $37.
Instant download, large print and audio included, 30-day money-back promise.
Get the guide — $37